
Summary
A payment plan agreement is a short written contract that splits an invoice into scheduled installments, recording the acknowledged balance, a deposit, the exact dates and amounts, autopay authority, and what happens if a payment is missed. The template below is free in Word and PDF, written for a business collecting its own invoice rather than for a lender.
- Free download: Three documents, no email required: the agreement, an arrangement offer letter, and an autopay authority, each in Word and PDF.
- The clauses that matter most: The customer's written acknowledgment of the balance, which removes the disputed-work defense, and the autopay authority, which is what turns a promise into a collection.
- The US legal line: Regularly offering consumers credit in more than four installments can make you a creditor under Regulation Z; business-to-business plans are exempt.
Download the payment plan agreement template
The payment plan agreement template comes as three free documents in Word or PDF: the signed agreement, an arrangement offer letter for an overdue balance, and an autopay authority. Have your lawyer check anything sizeable, and keep a signed copy with the invoice.
What makes this payment plan agreement different from a loan template?
This template is written for a business collecting on its own invoice, not for a lender extending credit, which is the gap every generic payment agreement template misses. Most free templates are loan documents, with a Debtor, a Creditor, and clauses about collateral. This agreement starts from the invoice. The parties are a Business and a Customer, the balance is tied to invoice numbers and original due dates, the deposit is the first installment, and the payment method clause assumes autopay, because arrangements that rely on the customer remembering to pay have a short life. Every clause maps to something your accounts receivable process can do afterwards: remind, charge, apply a fee, accelerate.
What should a payment plan agreement include?
A payment plan agreement should include ten clauses: balance and invoices, deposit, installment schedule, payment method and autopay, late or failed installments, default and acceleration, costs of recovery, no waiver, whole balance preserved, and governing law. The ones that do the real work are explained below; copy the wording and adapt the bracketed parts.
The Customer acknowledges owing the Business the total of [AMOUNT] under invoice(s) [NUMBERS] dated [DATES], confirms the underlying goods or services were delivered as agreed, and raises no dispute over the Balance.
The Customer will pay a deposit of [AMOUNT] ([%] of the Balance) on signing this Agreement. The deposit is the first installment under the Schedule.
The Customer will pay the remaining Balance in the installments set out in the Schedule. Time is of the essence for each payment date.
Payments will be collected automatically by [card / direct debit] under the authority signed with this Agreement. The Customer will keep a valid payment method on file for the life of the Schedule.
If an installment fails or is not paid on its date, the Business may charge a late fee of [AMOUNT] and interest at [RATE] on the overdue amount, and may re-attempt collection.
If an installment remains unpaid [7] days after its date, the Customer is in default and the whole remaining Balance, plus accrued fees and interest, becomes immediately due and payable without further notice.
The Customer will reimburse the Business for reasonable costs of recovery, including collection agency fees and legal costs, to the extent permitted by law. Accepting a late or partial payment does not waive the Business's rights or vary the Schedule. This Agreement is a payment arrangement, not a settlement, release, or novation.
How do I build the installment schedule?
Build the installment schedule from the total balance, the deposit percentage, the number of installments, and the frequency; the running balance column makes the schedule auditable at a glance. Enter the numbers, get the table, paste it into clause 3.
| Date | Amount | Running balance |
|---|
What mistakes cost you money when you write a payment plan agreement?
Three gaps in an agreement cost real money. The examples use the schedule builder's default plan: an $8,400 balance, a 25% deposit and four monthly installments.
- Leaving out the deposit. A 25% deposit is $2,100 ($8,400 × 0.25), which leaves $6,300 in four installments of $1,575 ($6,300 ÷ 4). With no deposit, you carry all $8,400 from the day you sign. Fix: keep the deposit as the first installment, as in the clause above.
- Leaving out default and acceleration. A customer pays the deposit and two installments ($2,100 + 2 × $1,575 = $5,250) and stops. You are owed $3,150 ($8,400 minus $5,250). Without the clause, usually only the missed $1,575 is due, and you chase the rest one month at a time. Fix: add the default clause with a 7-day cure window.
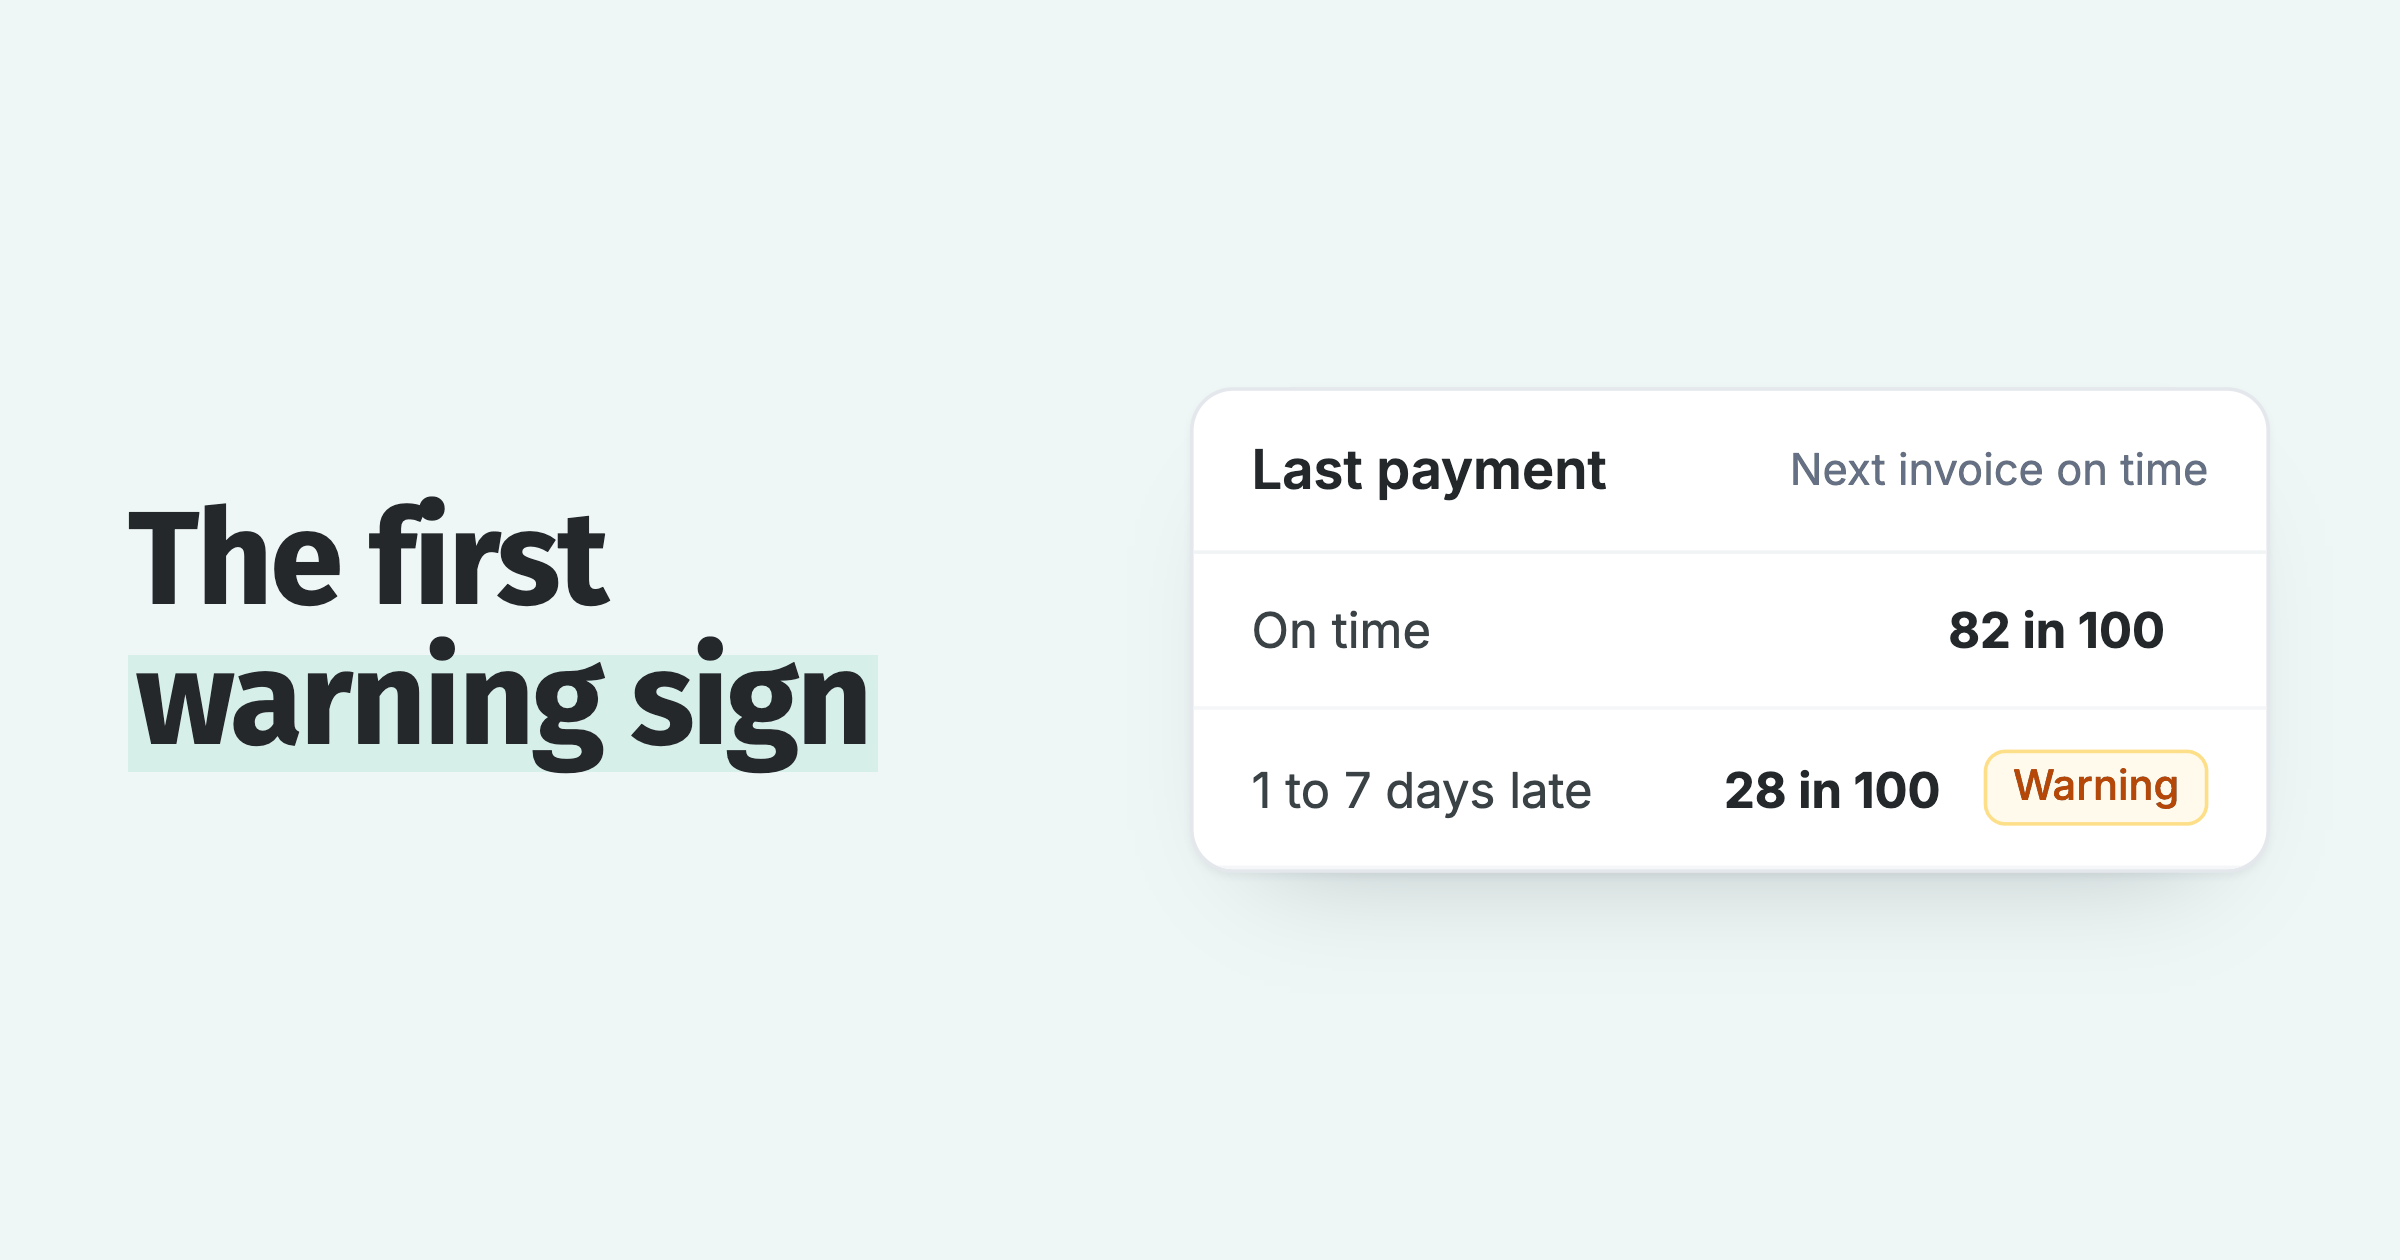
Relying on the customer to remember each date. Compared with sending nothing, the first overdue reminder gets about 19 more invoices in every 100 paid within a week, the second about 12 more, and the third to eighth 5 to 7 more each. Fix: sign the autopay authority with the agreement, and send a reminder before and after each date.
Source: our analysis of invoice data from over 1,000 Paidnice customers. See our reminder data.
Why is four installments a legal line in the US?
Four installments is the line because, under US Truth in Lending rules, a business that regularly extends credit to consumers, payable in more than four installments or carrying a finance charge, can meet the definition of a creditor under Regulation Z, with formal disclosure obligations to match. "Regularly" has a specific meaning (broadly, more than 25 such extensions in the preceding year), and business-purpose credit is exempt.
The practical read: B2B payment plans on invoices sit outside this regime. If your customers are consumers and installment plans are part of how you sell, keep plans to four payments or fewer, or get advice before scaling the program. Australia runs a similar split: the National Credit Code covers credit for personal and household purposes, and business-purpose arrangements generally sit outside it. This is the map of which lane you are in, not legal advice.
What happens after the agreement is signed?
After signing, a static template still needs someone to chase each installment date manually; Paidnice automates that from the same agreement, on the Xero or QuickBooks Online invoice, charging each installment through Stripe or Pinch Payments and reminding before and after every date.
Set the plan up on the actual invoice in Xero or QuickBooks Online and the schedule is written onto the invoice and the customer PDF, installments auto-charge under the authority you just collected, and a missed one makes the invoice overdue again so your late fee applies instead of your memory. Deposits work as the first installment, frequencies run weekly to quarterly, and uneven amounts (weekly payments with a final settlement) are fine. Plans are included on the Pro plan from US$99 a month, and customers see half as many late invoices in the first 30 days. The payment plans feature page has the two-minute tour, and the payment plan calculator models amortization and interest if you charge it.
Common questions
How do I write a payment plan agreement?
Name both parties and the invoices, state the balance with an acknowledgment that it is owed, set a deposit (20 to 30% is the norm for overdue balances), lay out every installment date and amount in a table, attach autopay authority, keep late fees and interest live on misses, add acceleration on default with a short cure window, and have both parties sign before the first payment date.
Is a payment plan agreement legally binding?
Yes. It is an ordinary contract: offer, acceptance, and consideration on both sides (you give time, they commit to a schedule). The acknowledgment clause also strengthens your position on the underlying debt if you ever need to enforce it. For large balances or consumer customers, have a lawyer review the wording for your jurisdiction.
Does it need to be notarised?
Usually not; signatures are enough for an ordinary commercial arrangement. Some businesses notarise very large balances as belt and braces, and some US states have specific requirements in consumer contexts, which is a question for your lawyer rather than a template.
What deposit should I ask for?
20 to 30% for an arrangement on an overdue balance, and up to 50% when the plan is agreed before work starts. The deposit tests commitment and caps your downside. A customer who cannot fund any deposit is asking for unsecured credit, not a payment plan.
Can I charge interest on a payment plan?
Generally yes for business customers, at your contractual rate: in the UK statutory interest of 8% plus the Bank of England base rate applies to late commercial payments regardless, in the US contract rates around 1 to 2% per month are typical subject to state caps, and in Australia and New Zealand the written clause is what creates the right. Consumer plans can trigger credit regulation; see the section above.
More on payment plans
This guide is part of a set on customer payment plans. Each piece stands alone; together they cover the whole system.
- Customer payment plans: the complete guide: when to offer them, when to decline, and how to structure the deal.
- Payment plans for overdue invoices: the deposit, term, and default playbook for money that is already late.
- Set up a payment plan in Xero and in QuickBooks Online: the platform mechanics.
- Payment terms and conditions templates: the terms that stop invoices going overdue in the first place.
Paidnice features in this article
About the editorial team
Denym started Paidnice in 2022 after customers paying late left his own business short on payroll. He has led it to $1 billion collected on time across more than 1 million invoices, and writes about credit control, late fees and getting paid on Xero and QuickBooks.
 App of the Year
