
Summary
Set up a payment plan for an overdue invoice by getting the debt acknowledged in writing, taking a 20 to 30% deposit now, splitting the rest into fixed installments on exact dates over three months, requiring autopay, and making the whole balance fall due if an installment is missed and not fixed within seven days.
- The numbers: A 20 to 30% deposit on signing, a term of three months and never more than six, and interest still running on the balance until it clears.
- The clock: Collection agency surveys put the odds of collecting a delinquent commercial account at 69% at three months, 51% at six, and 21% at twelve (Credit Research Foundation).
- The fix: Paidnice runs the plan on the original Xero or QuickBooks Online invoice, on the Pro plan, collecting each installment through Stripe or Pinch and reminding before every date.
When does a payment plan beat escalation on an overdue invoice?
A payment plan beats escalation on an overdue invoice when the customer acknowledges the debt, can pay a deposit today, and is worth keeping; escalate when any of those three is missing. Structured properly, a plan recovers money that demand letters and agencies often will not, and it keeps the customer. The customer who disputes the invoice, refuses a deposit, or has gone quiet is not a payment plan candidate, and a plan offered anyway just adds three months to the age of the debt.
The decision comes down to three signals you can test in one conversation:
| Signal | What it looks like | Right tool |
|---|---|---|
| Acknowledges the debt, short on cash | "We owe it, we just can't pay it all this month" | Payment plan |
| Acknowledges the debt, disputes the amount | "We'll pay, but not the late fees" | Settle the dispute first, then plan the agreed balance |
| Genuine distress, recovery unlikely in full | Insolvency signals, other creditors circling | Negotiated settlement now beats installments later |
| No acknowledgment, no deposit, no contact | Calls dodged, emails ignored | Letter of demand, then agency or court |
The deposit is the honesty test. A customer who is genuinely short of cash but intends to pay can nearly always find 20% today. A customer who will not put anything down is telling you where you sit on their creditor list, and a plan will not change that. Our customer payment plans guide covers the same decision for invoices that are not yet overdue, where plans are a sales tool rather than a recovery one.
What is a payment plan (and what is it not)?
A payment plan is a written agreement that lets a customer pay an overdue or large invoice in fixed installments on set dates instead of in one payment. The full balance stays owed. See the definition of a payment plan.
- A payment plan is not payment terms. Payment terms set the standard due date on every invoice. A plan replaces the due date on one balance with a schedule.
- A payment plan is not a settlement. A settlement accepts less than the full balance. A plan keeps the full balance and spreads it over dates.
- A payment plan is not a waiver. Any interest on the overdue balance keeps accruing until it clears unless you agree otherwise, so the agreement should say so. The plan changes when you are paid, not what is owed.
This matters for an overdue invoice because the signed plan is your evidence of the acknowledged debt. It is also what the missed-installment protocol below relies on.
How quickly should I act on an overdue invoice?
Act on an overdue invoice this week, not this quarter: the probability of collecting a delinquent commercial account falls to roughly 69% at three months past due, 51% at six months, and 21% at twelve, according to member surveys from Commercial Collection Agencies of America published by the Credit Research Foundation. Read those numbers the other way: a debt you could have collected at 90 days is a coin flip by 180, and close to a write-off by its first birthday.
Offer the plan before day 90. An invoice that is still unpaid 90 days after its due date has only about a 4 in 10 chance of being paid within a year of its due date.
That decay curve is the whole argument for the payment plan. A structured arrangement started today, with a deposit banked, converts a decaying receivable into a scheduled income stream while the odds are still on your side. It is also the argument for the deadline in your offer: the plan is available this week, on these terms, and silence takes it off the table.
How should an overdue invoice payment plan be structured?
The numbers that make an overdue-invoice plan stick: a 20 to 30% deposit on signing, a term of three months (never more than six), installments on exact calendar dates, autopay as a condition of the arrangement, and late-payment interest that keeps running until the balance clears. Each one exists because of a specific failure mode:
- The deposit proves intent and cuts your exposure on day one. For an overdue balance, push towards 30%: the debt has already demonstrated risk.
- The short term respects the decay curve. Six monthly installments means your last payment lands when the underlying debt is nine months old or more. Three is the target; six is the ceiling.
- Exact dates ("the 15th of each month, first payment 15 August 2026") make a miss detectable on the day it happens. "Monthly" does not.
- Autopay removes the customer's decision from every installment. A plan where the customer has to remember to pay is five more invoices to follow up on.
- Interest still running keeps the incentive to finish early and stops the plan becoming an interest-free refinancing of your patience.
- Acceleration means one missed installment makes the whole remaining balance due. Without it, a defaulted plan puts you back at the start, three months older.
All of this belongs in writing before the first installment moves. The signed document matters more here than on a pre-agreed plan, because the customer has already shown you what happens without one. Our payment plan agreement template has every clause explained plus free downloads: the agreement itself, an arrangement offer letter, and an autopay authority. Use the payment plan calculator to build a schedule that clears the balance inside the term.
What do I say to offer a payment plan on an overdue invoice?
Offer the arrangement in writing with the exact numbers: the balance, the deposit due this week, the installment amounts and dates, autopay, interest continuing, the seven-day cure window, and a deadline on the offer. By this point the customer is usually dreading the conversation more than you are. Two scripts cover it.
The promise-to-pay email, for the customer who has said some version of "cash is tight this month":
Subject: Invoice #1284: instalment arrangement
Hi Sam,
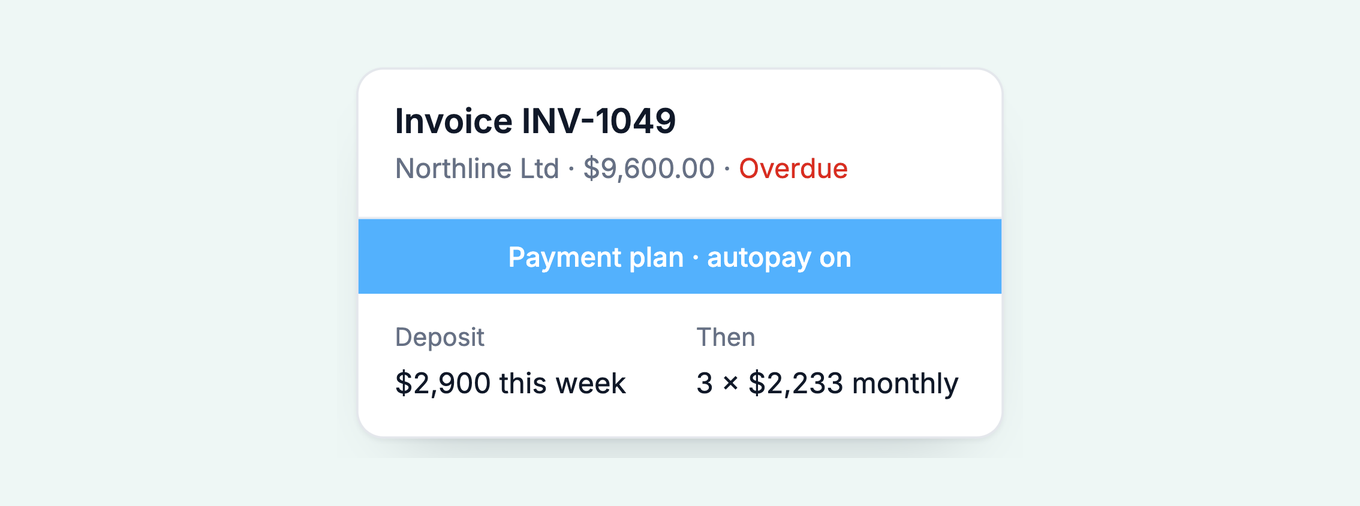
Thanks for being upfront about the situation. Rather than let this sit overdue, here is what we can do: split the $9,600 balance into a $2,900 deposit this week, then three monthly payments of $2,233 on the 15th of September, October, and November, collected automatically from a card or bank account you nominate.
Late-payment interest continues to apply to the outstanding balance until it clears, and if an instalment fails and isn't fixed within seven days, the remaining balance becomes due in full. I'll send the one-page agreement and the autopay authority today; the arrangement is confirmed once both are signed and the deposit has arrived.
This offer stands until Friday. If I don't hear back by then, I'll need to move the account to our normal escalation process, which neither of us wants.
Thanks,
Alex
The phone version is the same structure in three beats: acknowledge ("I know cash flow is tight"), offer the specific numbers ("deposit this week, three payments by autopay"), and set the deadline ("I can hold this offer until Friday"). Say the deposit figure out loud and then stop talking. The silence does the qualifying for you.
How do I record an overdue invoice payment plan in Xero or QuickBooks?
Record an overdue invoice payment plan against the original invoice: in Xero as part payments during bank reconciliation, in QuickBooks Online with Receive payment against the open invoice. Do not credit the original invoice and reissue it as three smaller ones, and do not build the schedule out of recurring sales receipts: both approaches detach the payments from the debt, and the second one double-counts your income.
- Xero: record each installment as a part payment against the original invoice. During bank reconciliation, use Find & Match, select the invoice, and use Split to apply the installment amount. The invoice stays open, showing the reducing balance, and your aged receivables stay honest. Full walkthrough in how to set up a payment plan in Xero.
- QuickBooks Online: record each installment with Receive payment against the open invoice, not as a new sales receipt. Progress invoicing is for milestone billing on estimates, and recurring sales receipts create new income each run. The full comparison of QuickBooks' native routes is in how to set up a payment plan in QuickBooks Online.
Getting this right is not bookkeeping pedantry. The open invoice with a reducing balance is your evidence of the acknowledged debt, your trigger for the missed-installment protocol, and the thing your accountant will thank you for at year end.
How do I manage a payment plan once it's agreed?
Once a plan is agreed, chase only the installment that is late, not the whole balance, so a single missed payment does not read as a full default to the customer.
- Before each date, send a short reminder with the amount and the date; after each collection, send a receipt showing the reducing balance.
- Once a month, send a one-line statement: installments paid, installments remaining, balance outstanding. It keeps the acknowledged debt visible.
- When an installment fails, follow up on that installment only, on the day, with the cure deadline stated. The rest of the schedule stands.
- Escalate only when the cure window closes: acceleration notice, then your standard escalation on the full balance.
In Paidnice this runs without a separate workflow. A payment plan moves the invoice due date to the next installment's date, and a missed installment makes the invoice overdue again, so the customer group's normal reminders, late fees, and interest apply from that date. A "Payment Plan Reminder" policy sends email before, on, or after each installment date, with an optional PDF and calendar invite.
What happens when an installment is missed?
A missed installment triggers a fixed protocol from the agreement: an automatic retry on day 0, a personal follow-up on day 1, a call on day 3, acceleration when the seven-day cure window closes, and standard escalation from day 10. The protocol below assumes autopay, a seven-day cure window, and an acceleration clause, which is exactly what the template agreement provides:
| Day | Action |
|---|---|
| Day 0 | Autopay fails. The payment is retried once; the customer gets an automatic notice that the installment did not go through. |
| Day 1 | Personal follow-up: card expiry and bank hiccups are common and innocent. "Your installment didn't go through, can you update your payment details today?" |
| Day 3 | Phone call if still unpaid. Restate the cure deadline in plain terms: paid by day 7, the plan continues; not paid, the full balance falls due. |
| Day 7 | Cure window closes. Acceleration notice goes out: the remaining balance is now due in full, with interest, per the agreement. |
| Day 10+ | Standard escalation on the full balance: letter of demand, then agency or court. The signed acknowledgment in the agreement makes this a much shorter argument. |
One clause keeps the protocol usable: no-waiver. In plain English, going easy once does not rewrite the deal. If you accept a payment three days late in month two, you can still enforce the exact dates in month three. Without that clause, every kindness becomes a precedent.
Does interest keep running while the plan runs?
Yes. Interest on the overdue balance should keep accruing until it clears, and the agreement should say so. What you can charge depends on where you trade:
- UK: for business-to-business debts you can charge statutory interest at the Bank of England base rate plus 8% per annum (the base rate in force on 30 June or 31 December applies for the following six months), plus a fixed recovery sum of £40, £70, or £100 GBP depending on debt size, under the late commercial payments rules. A contractual rate in your terms can substitute for the statutory scheme.
- US: interest is contractual, and state usury caps vary. Keep consumer arrangements to four installments or fewer unless you want a conversation about credit regulation; the template guide covers where that line sits.
- Australia and New Zealand: contractual. Whatever rate your terms of trade specify is what you can enforce, which is a good reason to specify one.
Frame interest to the customer as the cost of time, not a punishment: the plan spreads the payments, the interest prices the delay, and settling early always costs less.
How does Paidnice run an overdue invoice payment plan?
Paidnice runs the overdue invoice payment plan on the original Xero or QuickBooks Online invoice: you set the deposit and the schedule, the customer enables autopay in the payment portal, and each installment collects through Stripe or Pinch Payments on its date. Stripe payment plans work on the QuickBooks Online connection as well as Xero.
Reminders go out before each installment, late fees and interest stay live, and a miss makes the invoice overdue again so your escalation workflow picks it up instead of your memory. Customers get 8 in 10 invoices paid within the first 60 days of using Paidnice, and the collections conversations that used to feel like pressure start to feel like customer service. Payment plans are included on the Pro plan, from US$99 a month. See how it works on the payment plans feature page, or the results in our customer stories. Close the gap between invoice and payment, even when the payment arrives in installments.
Common questions
How long should I give a customer to pay an overdue invoice?
Give a specific short deadline, not more patience. For a customer who can pay in full, seven days is standard. For a customer who cannot, move straight to the arrangement conversation: a deposit this week plus a three-month schedule recovers more than another 30 days of silence, because collectability decays fast after 90 days overdue.
Can I charge interest on an overdue invoice payment plan?
Yes, and you generally should, so the plan prices the delay rather than rewarding it. In the UK, statutory interest for B2B debts is the Bank of England base rate plus 8% per annum unless your contract substitutes its own rate. Elsewhere it is what your terms of trade specify, subject to local caps. State the rate in the signed agreement.
How long should a payment plan be for an overdue invoice?
Three months is the target, six is the maximum. Longer terms collide with the collectability decay curve: agency surveys put the odds of collecting at 51% once an account is six months delinquent, so a 12-month plan on an already-overdue balance is a bet against your own data.
When should I write off an overdue invoice instead?
When the cost of recovery exceeds the realistic return: the customer is insolvent, disputes the debt with no acknowledgment in writing, or the balance is small enough that agency fees and your time outweigh it. A refused deposit is often the deciding signal. Write it off, claim the tax treatment your accountant advises, and tighten terms for the next customer.
How long do I have to collect an overdue invoice?
There is a limitation period on suing for a simple contract debt: six years in England and Wales, New Zealand, and most Australian states, and typically three to ten years in the US depending on the state. A written acknowledgment of the debt, like the one in a signed payment plan agreement, generally restarts the clock, which is one more reason to get it signed.
More on payment plans
Each piece below stands alone; together they cover the whole system.
- Customer payment plans: when to offer them, when to say no, and the structure that protects you.
- How to set up a payment plan in Xero: what Xero does natively, what it cannot, and the clean workflow.
- How to set up a payment plan in QuickBooks Online: Affirm, recurring receipts, progress invoicing, and the comparison.
- Payment plan agreement template: every clause explained, free downloads, and the schedule builder.
- Accounts receivable software with payment plans: six tools compared on the due date, the invoice total and automatic charging.
Paidnice features in this article
About the editorial team
Denym started Paidnice in 2022 after customers paying late left his own business short on payroll. He has led it to $1 billion collected on time across more than 1 million invoices, and writes about credit control, late fees and getting paid on Xero and QuickBooks.
Ashley is a co-founder and lead developer of Paidnice and has built accounting software for more than 10 years. He builds the ledger connections that put reminders, late fees and payments into Xero, QuickBooks and ERPs such as NetSuite and Business Central. Before Paidnice he co-founded A2X, ecommerce accounting software for Xero and QuickBooks.
 App of the Year
