
Debtor management software in New Zealand automates invoice reminders, tracks accounts receivable and recovers overdue payments from the invoices already in your Xero organisation. Xero's own reminders cover the first stretch of that job. You need a dedicated app once you want scheduled statements, a late fee or interest charge that stands on your terms of trade, and escalation that does not depend on someone remembering.
This guide covers which of those apps fits your situation and your business best.
Xero's own debtor management runs out once you need scheduled statements, a fee on your terms of trade, or escalation to a named person. New Zealand small businesses were paid in 23.2 days on average in June 2026, 5.1 days past the due date, according to Xero Small Business Insights. By world standards that is prompt, and it is why many Kiwi businesses never look past Xero's built-in reminders.
The sector spread tells a different story. Manufacturing waited 33.7 days in the same month and hospitality 13.2, a gap of 2.5 times. Our own breakdown of the same dataset is in accounts receivable statistics for New Zealand, by industry and by region.
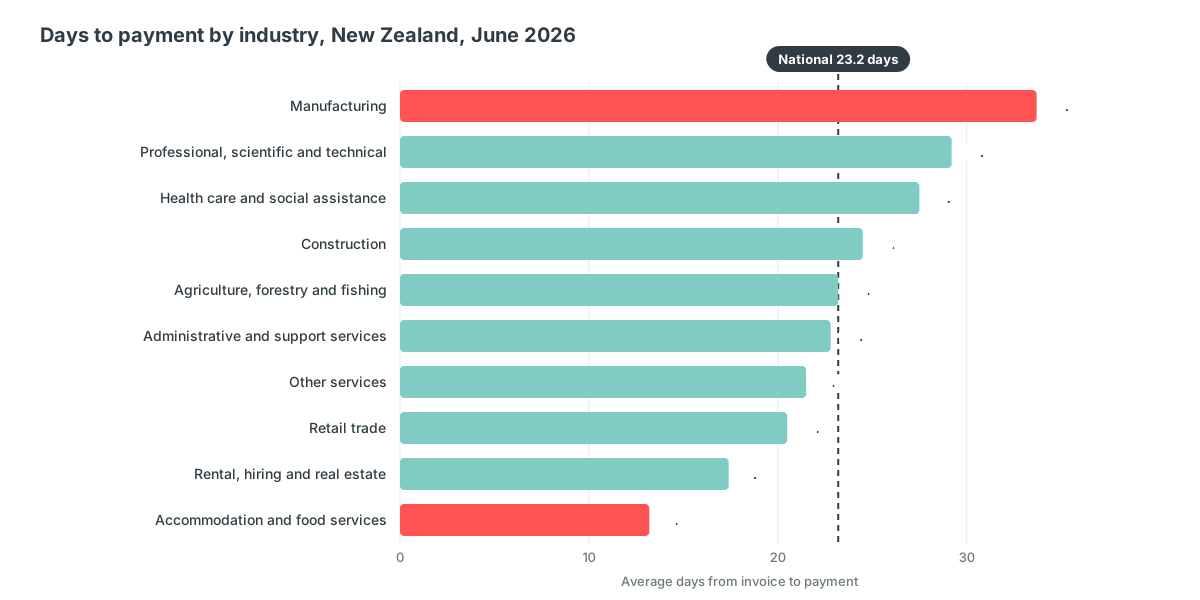
The question is whether your customers pay late. A manufacturer on 20th of the month terms with a debtor book that runs at 34 days has a cash flow problem the national average hides.
Xero gives every New Zealand organisation four debtor management tools. Each does one job, and each stops in the same place.
What none of them do: charge a fee or interest, escalate to a named person, pause on a disputed invoice, or take payment on a plan.
Two signs you have hit the ceiling: the overdue list stops shrinking between runs, and someone is chasing by hand after the fifth reminder. At that point an app costs less than the hours it replaces.
Debtor management software automates invoice reminders, tracks accounts receivable and recovers overdue payments. Four capabilities decide whether it works in a New Zealand business.
Those four make a tool usable. What makes it worth buying is everything Xero cannot do at all: posting a fee or interest charge to the ledger on your terms of trade, taking payment on an instalment plan, escalating to a named person, pausing on a disputed invoice, and giving the customer a portal to settle in.
That is the dividing line in this category. A chasing tool sends better emails. An automation platform enforces the terms you already agreed, and the six below are split between the two.
The six tools below are not competing for the same job. Start here rather than with the list, because the right answer is decided by your size, your ledger and what your real bottleneck is.
| If this is you | Start with |
|---|---|
| Larger business, happy to sign a longer contract, and you need credit checks as well as chasing |  |
| You want a person on the phone to your debtors, and you are already in the CreditorWatch world |  |
| Steady invoice volume on Xero, statements going out on the 20th, and you want reminders, fees and escalation in one plan |  |
| Distributor or wholesaler with MYOB or an ERP in the stack |  |
| Accounting or legal practice chasing fee notes, with fee funding alongside |  |
| A handful of old debts you want run through a fixed collection process, without an agency commission |  |
Debtrak also appears in New Zealand searches for this category: its target is enterprise and government collections, its integration is banking and government systems rather than Xero, and its key feature is workflow automation, so it is a different purchase from the six below.
Each tool is placed against the job it does best, rather than scored out of ten. A $700k trades business and a $40m distributor are buying different products, so a single winner would be wrong for most readers.
We checked vendor materials in September 2026, and prices are as at September 2026. Prices change; verify current pricing before you buy.
If you are a larger business and credit checks matter as much as chasing
The most established suite here, founded in the UK in 2014, and the one to pick if vetting customers matters as much as chasing them. The pricing tiers are built for businesses well past the typical New Zealand small business.
The limitation. It is the oldest product on this list and the least configurable. The late fee rule is global. Statements go monthly on a fixed day, with recipients and senders you cannot change.
Pricing on company revenue is the other thing to model carefully. A low-volume, high-value business can land on a £599 tier for a handful of invoices a month.
Best for: businesses past about £4m that want credit data and chasing in one product and can absorb a rigid configuration.
If you want a person on the phone to your debtors
Formerly Debtor Daddy, founded in Canterbury in 2012 and acquired by the Australian credit bureau CreditorWatch in 2022. The reminders are standard; the reason to buy is the New Zealand-based calling team you can add on top.
The limitation. No late fees or interest, so the leverage side of debtor management is missing. The Xero sync runs once a day, so a payment this morning can still be chased this afternoon. Review activity has been thin since the rebrand.
Best for: businesses that want phone calls made on their behalf and are happy to take a custom quote for it.
If you send a lot of invoices and statements, and you live in Xero
Paidnice is debtor management software for Xero that automates invoice reminders by email and SMS from your own domain, scheduled statements, late fees and interest on your terms of trade, payment plans, a customer payment portal and escalation, in one plan. Built in Auckland, natively on Xero, and the value option when you send steady volume.
The limitation. No credit checks. There is no bureau data, no risk score from a bureau and no monitoring feed, so vetting new accounts has to happen somewhere else. Native support is Xero and QuickBooks Online only; MYOB and other ledgers are a Custom-plan conversation.
Paidnice is built for two ledgers rather than eight. That is why the Xero integration goes deeper than a sync, and why a MYOB business should look at ezyCollect on this list. Customers cut their average wait for payment in half, within 30 days.
Best for: New Zealand businesses on Xero with steady invoice and statement volume that want the whole receivables process in one plan. Paidnice's own debtor management software for New Zealand page has the local detail.
If you are a distributor on MYOB or an ERP
Long established in the Australian and New Zealand mid-market, now owned by Sidetrade, and strongest where the ledger is MYOB or an ERP rather than Xero alone.
The limitation. An annual commitment plus a setup fee is a barrier for a business that wants to try before it buys, and there is no late fee or interest automation. Demand letters and collection referrals are charged on top.
Best for: AU and NZ distributors with an ERP in the stack and a debtor book in the hundreds.
If you are an accounting or legal practice chasing fee notes
Built for accounting and legal firms rather than for businesses in general, with fee funding, engagement letters and identity verification sold alongside the debtor management. Headquartered in Melbourne and Auckland.
The limitation. The product reads as reminders plus payments, with no scheduled statements, fees or escalation described in public materials. Pricing is opaque and the review record is thin, so ask for references from firms your size.
Best for: practices on MYOB AE or GreatSoft that want fee funding and debtor follow-up from one vendor.
If you have a handful of old debts and want a fixed process, not an agency
A New Zealand self-service debt recovery platform rather than a receivables tool. You load a debt that is already overdue, a 21-day collection process runs, and the money is paid to you directly with no commission taken.
The limitation. It only starts once an invoice is 30 days over. There are no pre-due reminders, no statements, no payment plans and no fees, so it does nothing to stop the next invoice going 30 days over.
Best for: a business with a few stubborn debts and no appetite for an agency's commission.
Each tool's target buyer, the ledgers it integrates with, its key feature, whether it can post a charge back into your ledger, and what it costs. The key feature column separates a tool that sends better emails from a platform that runs the process.
| Tool | Target | Integration | Key feature | Posts fees to the ledger | Entry cost |
|---|---|---|---|---|---|
| Chaser | £4m and up | Xero, QuickBooks, Sage, NetSuite, Dynamics 365, SAP | Credit checks alongside email and SMS chasing | One global rule | NZD 399/mo |
| CreditorWatch Collect | Owner-operators, CreditorWatch users | Xero (24-hour sync), MYOB, QuickBooks | Human calling team, collection referral | No | Not published |
| Paidnice | $1m to $20m on Xero or QuickBooks Online | Xero, QuickBooks Online | Reminders, statements, fees, plans, portal and escalation from the ledger | Yes, per group | NZD 109/mo ex GST |
| ezyCollect | AU and NZ distributors | Xero, QuickBooks Online, MYOB, NetSuite, SAP Business One, Pronto | Credit insights, demand letters, collection referral | No | Last published A$275/mo plus setup |
| FeeSynergy Collect | Accounting and legal firms | Xero, MYOB AE and AO, GreatSoft | Fee funding and practice management integration | Not published | Not published |
| iCollect | NZ small business, old debts | Xero | Fixed 21-day collection process, no commission | Not published | From NZ$39/mo plus GST |
A cell reads "not published" where the vendor documents nothing either way, rather than where a capability is known to be absent. Chaser's row reads "one global rule" because the fee exists but cannot vary by customer group.
The fees column is the one worth a second look. Reading your ledger and marking an invoice paid is a sync. Posting a fee into Xero is a deeper integration, and it is why a charge raised in Paidnice reaches your customer's accounts payable rather than sitting on a dashboard.
You can charge interest on a late invoice in New Zealand if your terms of trade say so. New Zealand has no statutory late payment interest rate for business-to-business invoices, so there is no default rate to fall back on. The charge stands on the terms of trade your customer accepted, and the amount should be reasonable.
That is why the fees column above matters. A tool cannot look up a rate for you, because there is none. It has to apply the fee you agreed, at the level you agreed, and put it somewhere your customer will see it. For what counts as reasonable and how to word the clause, see how much you can charge for late fees in New Zealand.
If a debt goes all the way to a claim, the Disputes Tribunal now hears claims up to $60,000, up from $30,000 since 24 January 2026, according to the Ministry of Justice. A fee already sitting on the ledger is part of the evidence.
Whichever tool you choose, the setup follows the same three phases. Most of the value arrives in the first, before any email is sent.
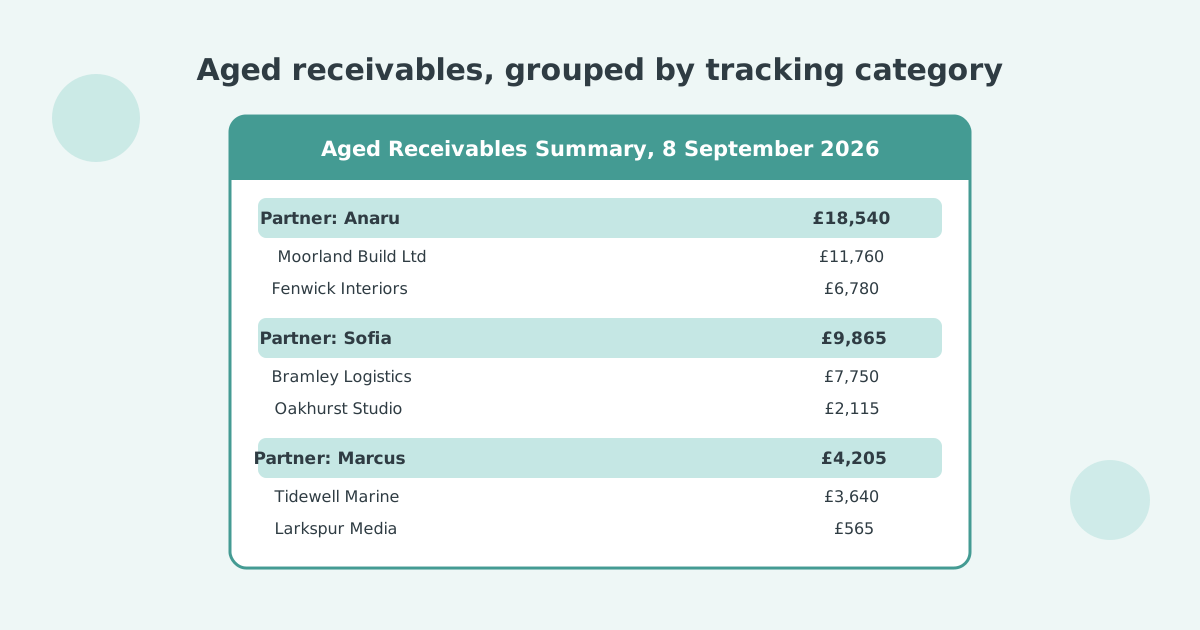
The audit phase is where the sector spread shows up in your own book. Pull the Aged Receivables report by customer before you connect anything and sort by average days to pay. In a mixed book it is common to find one group paying on the 20th and another running at 40 days, which means the configuration phase needs two policies, not one.
Two questions decide the shortlist: how big the ledger is, and what the problem is. Five common New Zealand situations and where they land.
| Your situation | What to look at |
|---|---|
| Under $500k, fewer than 25 invoices a month | Automated reminders and a scheduled monthly statement run. That alone is a full use case, and fees can come later. |
| Steady invoice volume on Xero, statements going out on the 20th | Look for scheduled statements, fees and plans in the base product rather than as paid add-ons. |
| Extending trade credit to accounts you cannot vet | Credit data. This is the one job the cheaper tools do not do. |
| Manufacturing or professional services, debtor days above 30 | Enforcement. Your terms are being ignored, so the tool has to apply a fee and escalate to a named person. |
| A few debts already past 60 days and nothing new going wrong | A collection process for those debts, then a receivables platform so the next invoice never gets there. |
For the general shape of the category, and the tools that serve other markets, see debtor management software. For the native-versus-app decision on its own, see Xero invoice reminders vs a credit control app: what changes.
Six questions in a demo separate tools that look identical on a feature grid, because every vendor writes to the same checklist. None of them appear on a pricing page.
The question that changes the most demos is the second one. Ask the vendor to raise a late fee during the call and then show you that fee sitting in Xero as an approved invoice against the customer. A fee on a dashboard reaches nobody. A fee on the ledger reaches your customer's payment run.
Most of this decision comes down to two questions: how much of the process you want automated, and what your ledger looks like. If you still cannot tell, ask us.
We would rather point you at the right tool than sell you the wrong one. Three of the six above do things Paidnice does not, and we will tell you when one of them is the better answer.
What is debtor management?
Debtor management is the process of making sure customers who owe you money pay on time: setting terms of trade, sending invoices and reminders, tracking accounts receivable by age, applying any agreed fees, and escalating overdue accounts. Debtor management software automates the reminders, statements and follow-up from the invoices already in your accounting software.
What is the best online accounting software for small businesses in New Zealand?
Xero is the ledger every tool on this list connects to, and the source of the New Zealand payment data in this guide. MYOB and QuickBooks Online are the other cloud options, though QuickBooks Online is not localised for New Zealand tax. Debtor management software sits on top of whichever one you use.
How much do collection agencies charge in NZ?
Rates vary by agency, by the age and size of the debt, and by whether they charge a commission on what is recovered or a fixed fee per debt. None of the six tools above is a collection agency. Two of them, CreditorWatch Collect and ezyCollect, can refer a debt to one, and iCollect works alongside one for demand letters.
What are some good debt collection apps?
For recovering a debt that is already overdue, iCollect runs a fixed collection process from Xero, and CreditorWatch Collect and ezyCollect can hand a debt to a collection partner. For stopping invoices reaching that point, Paidnice and Chaser automate reminders, statements and fees from the ledger so fewer debts need collecting at all.
Can I charge late payment interest in New Zealand?
Yes, if your terms of trade provide for it. New Zealand has no statutory late payment interest rate for business-to-business invoices, so the charge stands on your terms of trade and the amount should be reasonable. Paidnice applies the fee or interest to the Xero invoice once it is in your terms. Clause wording is in late fees in New Zealand.
Is there a free trial?
Paidnice has a free action period rather than a timed trial. Signing up is free, the first 20 actions are free with no time limit, and no card is needed. An action is anything Paidnice performs: an email or SMS sent, an escalation created or a late charge generated. Chaser, CreditorWatch Collect, ezyCollect and FeeSynergy each offer a time-limited trial.
Paidnice is accounts receivable automation that enforces your payment terms, trusted by thousands of businesses on Xero and QuickBooks. Credit control and debtor management, run for you.
Try it Now - It's FreeNo card required.
Optimize your cash flow with our suite of financial tools designed for AR professionals. Calculate DSO, aging analysis, late fees, and more.