Summary
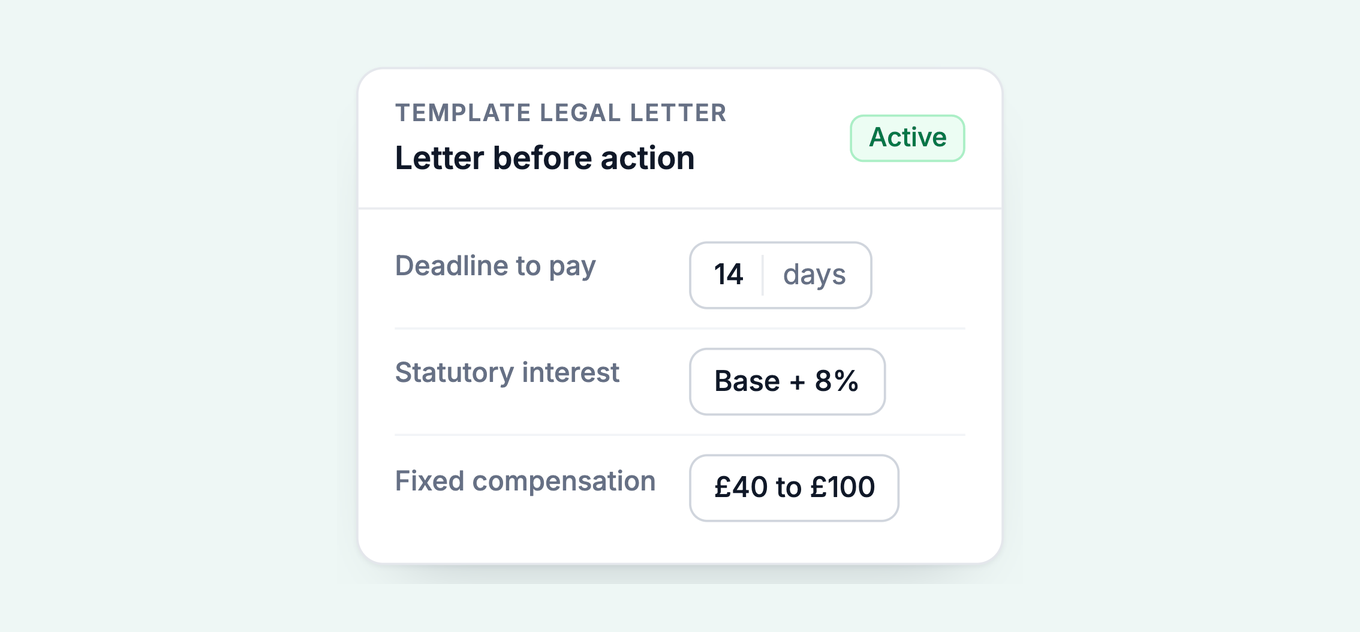
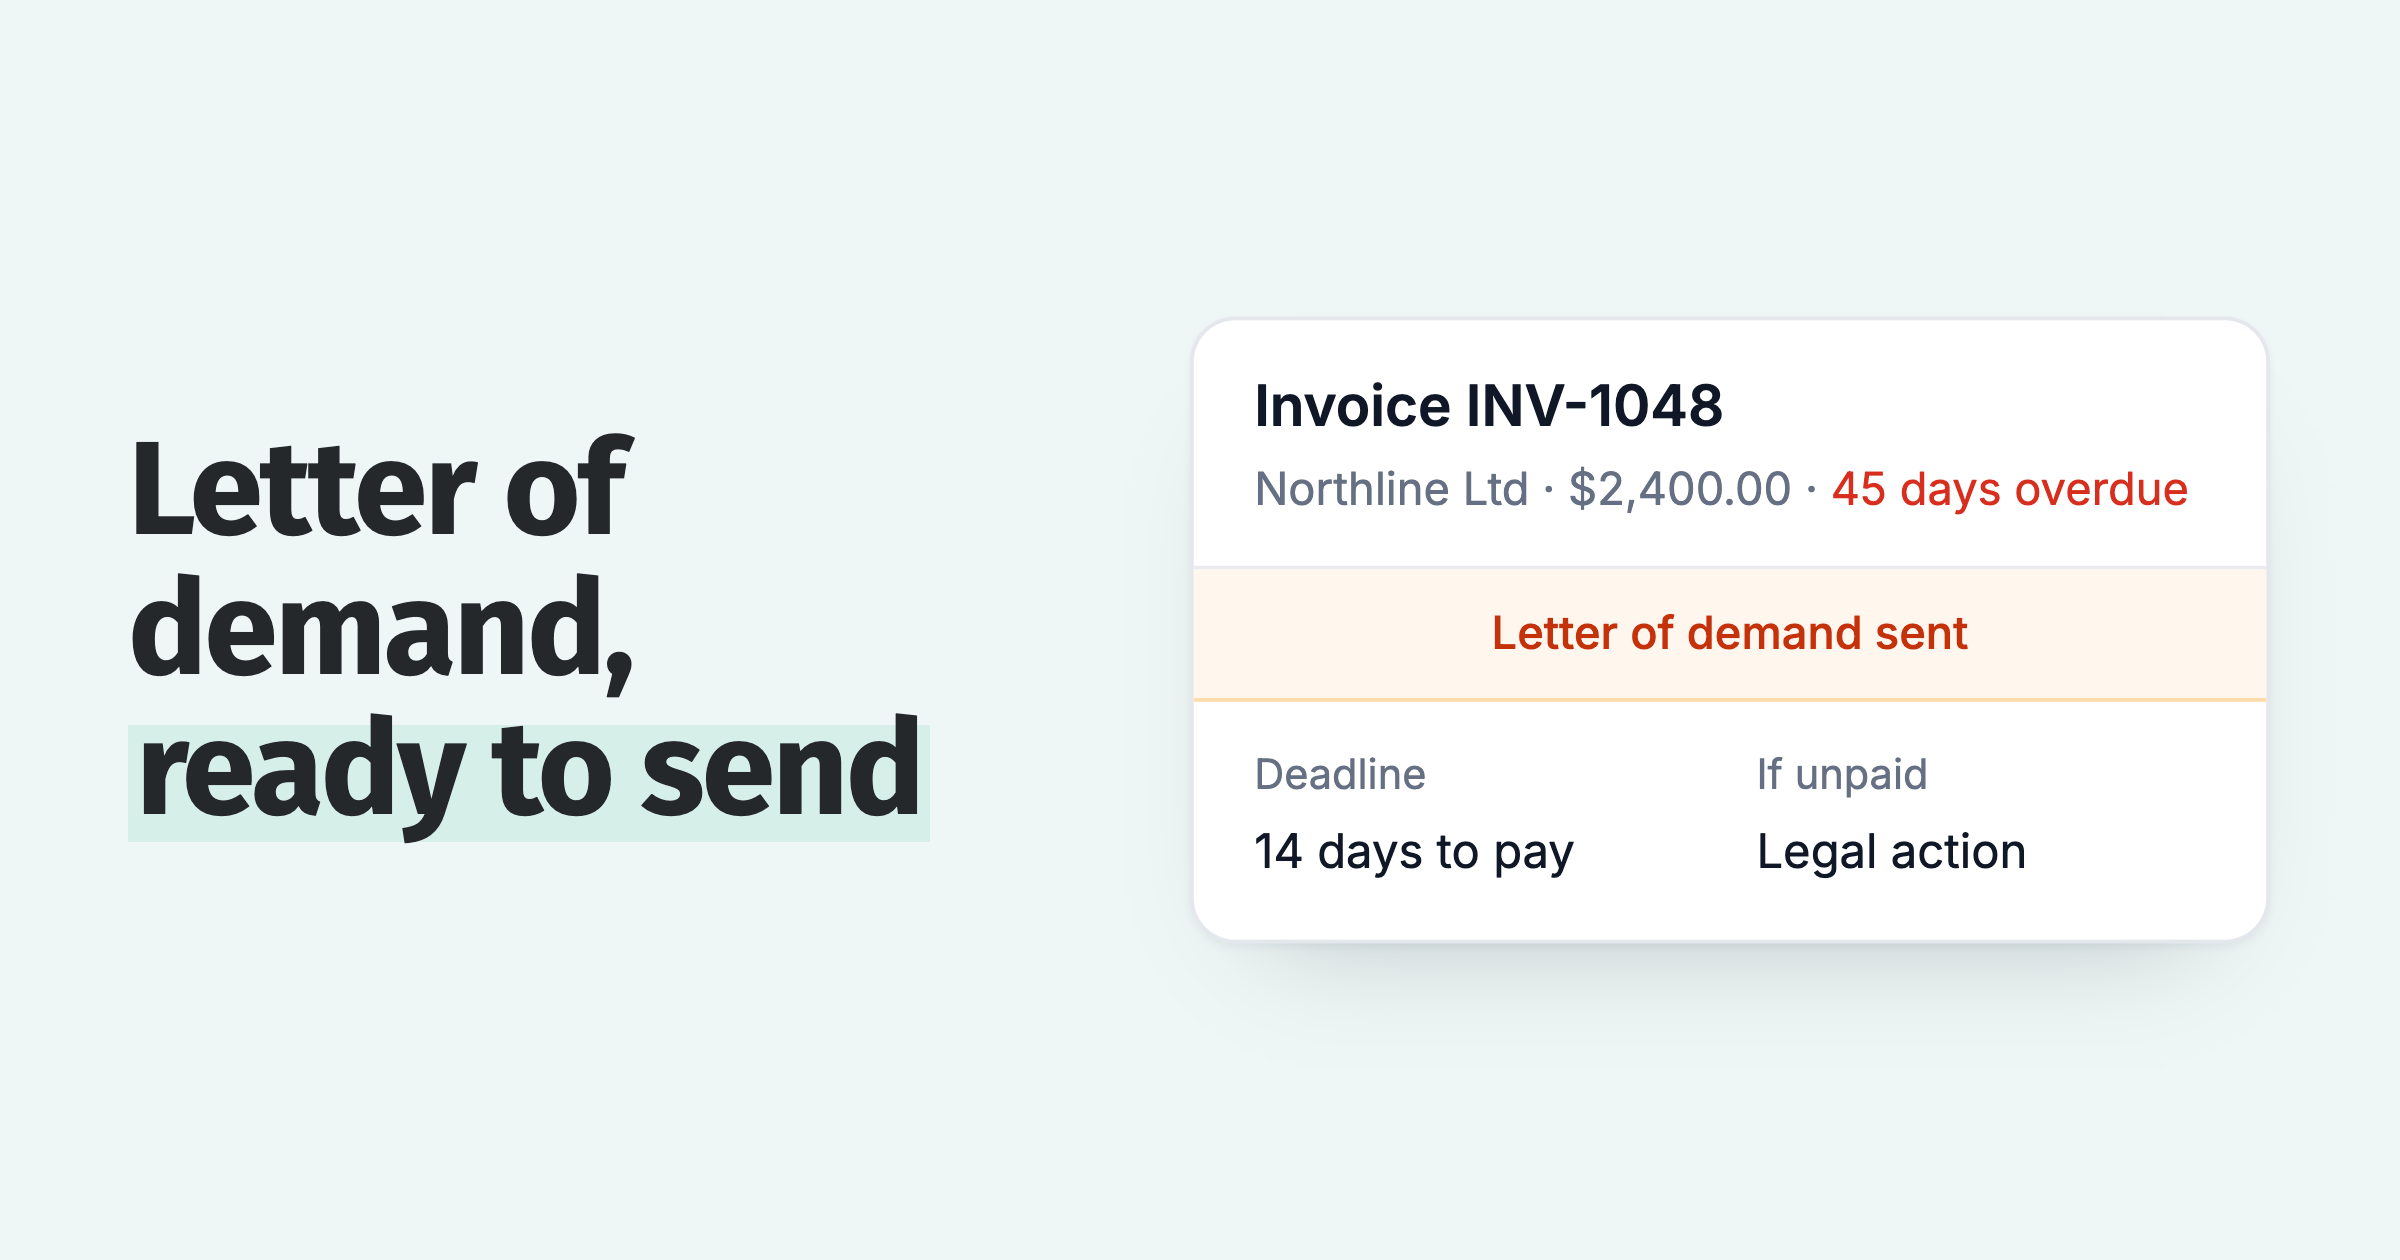
A letter before action (LBA) is a formal written warning that legal action will follow if a debt is not paid, and it is the final step the courts in England and Wales expect before a county court claim. Give 14 days for a business debt, and 30 days where the debtor is an individual or sole trader.
- What it must contain: The debt, the exact amount, a firm deadline, and the interest and compensation you are claiming under the Late Payment of Commercial Debts (Interest) Act 1998.
- The interest ceiling: On a commercial debt you can claim statutory interest at the Bank of England base rate plus 8% a year, plus fixed compensation of £40 to £100 per invoice.
- Where Paidnice fits: Paidnice automates every step up to the letter before action, including UK statutory interest, then prints and posts the letter for US$2.00 (£1.50 in the UK) on Pro plans and up. A solicitor-signed letter is available on request.
This is general information to help you understand the process, not legal advice. Where it matters, it points you to the official source: gov.uk, the Ministry of Justice Pre-Action Protocol for Debt Claims, and the Late Payment of Commercial Debts (Interest) Act 1998. For a debt that is large, disputed, or complex, take advice from a solicitor.
Before you send, it is also worth checking the UK insolvency tracker to see how many companies in the debtor's industry are failing.
What is a letter before action?
It is the point where a chase becomes a legal step. Earlier reminders are about prompting payment. A letter before action is you putting the debtor on notice that the next move is a claim in the County Court, and giving them a last clear chance to settle or reply.
The courts in England and Wales expect both sides to try to resolve a dispute before anyone issues a claim. The letter before action is how you show you did that. It sets out the debt, the deadline, and the consequence in one place, in writing, so there is a record.
Free: Payment reminder email templatesCopy the reminder emails for before, on and after the due date.Is a letter before action legally required?
The general expectation comes from the Practice Direction on Pre-Action Conduct and Protocols, published by the Ministry of Justice. It says parties should exchange enough information to understand each other's position and try to settle before going to court. A judge can penalise a claimant who ignored that, usually on costs or interest, even where the claim itself succeeds.
Where the money is owed by an individual or a sole trader, there is a stricter rule: the Pre-Action Protocol for Debt Claims. It sets out exactly what your letter (there called a Letter of Claim) must include, and paragraph 3.4 says the creditor may start proceedings only if the debtor has not replied within 30 days of the date on the letter. Paragraph 1.1 states the protocol does not apply to business-to-business debts unless the debtor is a sole trader, but the general pre-action conduct rules still do.
What must a letter before action contain?
Use this checklist before you send. It covers what the Pre-Action Protocol for Debt Claims looks for and what a judge will expect to see if the matter reaches court.
What a letter before action must contain
- Your business name and contact details, and the debtor's correct legal name and address.
- The invoice number or numbers, the date each was issued, and the exact amount outstanding.
- The original due date, and a short note of the reminders you have already sent.
- A plain statement that this is a letter before action.
- A firm deadline to pay or respond: 14 days for a business, 30 days for an individual or sole trader.
- The interest and compensation you are claiming, and how it is worked out.
- How to pay, and how to raise a dispute or propose a payment plan.
- A note that you will issue a county court claim if the deadline passes.
Do you need a solicitor for a letter before action?
A letter before action is a letter, not a court filing, so nothing in the pre-action rules requires a solicitor to draft or send it. What the court looks for is the content: the debt, the amount, the deadline and the consequence. A letter from a law firm can signal that you are prepared to follow through, and for a debt that is disputed or large enough that a claim would run past the small claims track, a solicitor's fee is usually money well spent. For an ordinary unpaid invoice, send your own, keep a dated copy, and involve a solicitor only if it is ignored. A firm chasing its own fee invoices can use accounts receivable software for law firms.
How long should a letter before action give to pay?
The 14-day figure is the common practice for a straightforward commercial debt between two businesses. It is long enough to be reasonable and short enough to keep pressure on. The 30-day figure is not optional when your debtor is a person or a sole trader: the protocol sets it, and a court will expect you to have honoured it.
Whatever deadline you choose, count from the date on the letter, allow time for the post, and hold to it. A deadline you quietly extend twice teaches the debtor that the next one is soft too.
The letter before action template
This template is written for a commercial debt and pre-wires the statutory interest wording under the Late Payment of Commercial Debts (Interest) Act 1998. It is a starting point, not a substitute for advice on a specific dispute. Work out the interest and compensation with the UK statutory interest calculator and enclose that figure.
[Your business name]
[Your address]
[Email] · [Phone]

[Date]

[Debtor name]
[Debtor address]

Dear [Name],

LETTER BEFORE ACTION

Re: Outstanding invoice(s) [invoice number(s)]

Our records show that the following amount remains unpaid:

  Invoice [number], dated [date]: [amount]
  Total now due: [amount]

Payment was due on [due date]. Despite our earlier reminders, we have
not received payment or a response.

This is a formal letter before action. If we do not receive payment in
full, or a proposal to settle, within [14 / 30] days of the date of this
letter, we intend to issue a claim against you in the County Court
without further notice.

As this is a commercial debt, we are entitled to claim interest and
compensation under the Late Payment of Commercial Debts (Interest)
Act 1998:

  Statutory interest at 8% per year above the Bank of England base
  rate, calculated daily from the date the payment fell due.
  Fixed compensation of [£40 / £70 / £100], set by the size of the debt.

The interest and compensation due on this debt is set out in the
enclosed calculation.

To avoid a court claim, please pay [total amount] to:
  [Bank name], sort code [xx-xx-xx], account [xxxxxxxx]
  Reference: [invoice number]

If you dispute this debt, or wish to propose a payment plan, please
contact us in writing by [date] so we can try to resolve this without
going to court.

Yours [sincerely / faithfully],

[Your name]
[Your business name]
General information only. Adjust the wording to your situation, and take advice from a solicitor for a large or disputed debt.
Can you add interest to a letter before action?
That is the ceiling. The Act entitles a business owed money by another business to interest at 8% above the Bank of England base rate, and you should not claim more than that. The reference rate is fixed twice a year: the base rate in force on 30 June or 31 December applies for the following six months, rather than moving day to day. With the base rate at 3.75%, the statutory rate for the half-year from 1 July 2026 is 11.75%. Paidnice can lock the base rate for each six-month period as the Late Payment Order sets it, or follow the Bank of England base rate dynamically as it moves; the mechanism is explained in how to auto-update the Bank of England interest rate.
On top of the interest, the Act allows fixed compensation for the cost of recovering the debt: £40 for a debt under £1,000, £70 for a debt of £1,000 up to £9,999.99, and £100 for a debt of £10,000 or more. It is one fixed sum per unpaid invoice.
Because the numbers depend on the invoice amount and the number of days late, do not guess them in the letter. Run them through the UK statutory interest calculator, enclose the figure, and the debtor sees the real cost of not paying. If you also charge your own late fees, the rules on what you can apply are in late payment fees for UK businesses.
What mistakes cost you money when you send a letter before action?
Three mistakes cost days or money. This is general information, not legal advice.
Giving a sole trader 14 days. Paragraph 3.4 of the Pre-Action Protocol for Debt Claims lets a creditor start proceedings if the debtor has not replied within 30 days of the date on the letter. A claim after 14 days leaves 16 of those days unused (30 - 14), and under paragraph 7.1 a court takes non-compliance into account.
Fix: give 30 days to an individual or sole trader.
Claiming the fixed sum once for several invoices. Section 5A of the Late Payment of Commercial Debts (Interest) Act 1998 sets the sum by the size of each qualifying debt. Three unpaid invoices of £1,500 each carry £70 each, £210 in total (3 × £70). Claiming £70 once leaves £140 unclaimed.
Fix: list each invoice and its sum in the letter.
- Asking for the invoice total only. On a £5,000 invoice 60 days late, interest at a base rate of 3.75%, for example, is 11.75% a year (3.75% + 8%), about £96.58 (£5,000 × 0.1175 × 60 ÷ 365), and the fixed sum is £70. That is £166.58 left out. Fix: enclose the figure from the UK statutory interest calculator.
What happens if the letter before action is ignored?
For a straightforward money claim, start at gov.uk's Make a court claim for money page, which takes you to the right online service, including Money Claim Online (MCOL). You pay a court fee, which is scaled to the size of the debt and can often be added to the amount you are claiming back. The court then serves the claim on the debtor, who has a set period to pay, admit, or defend.
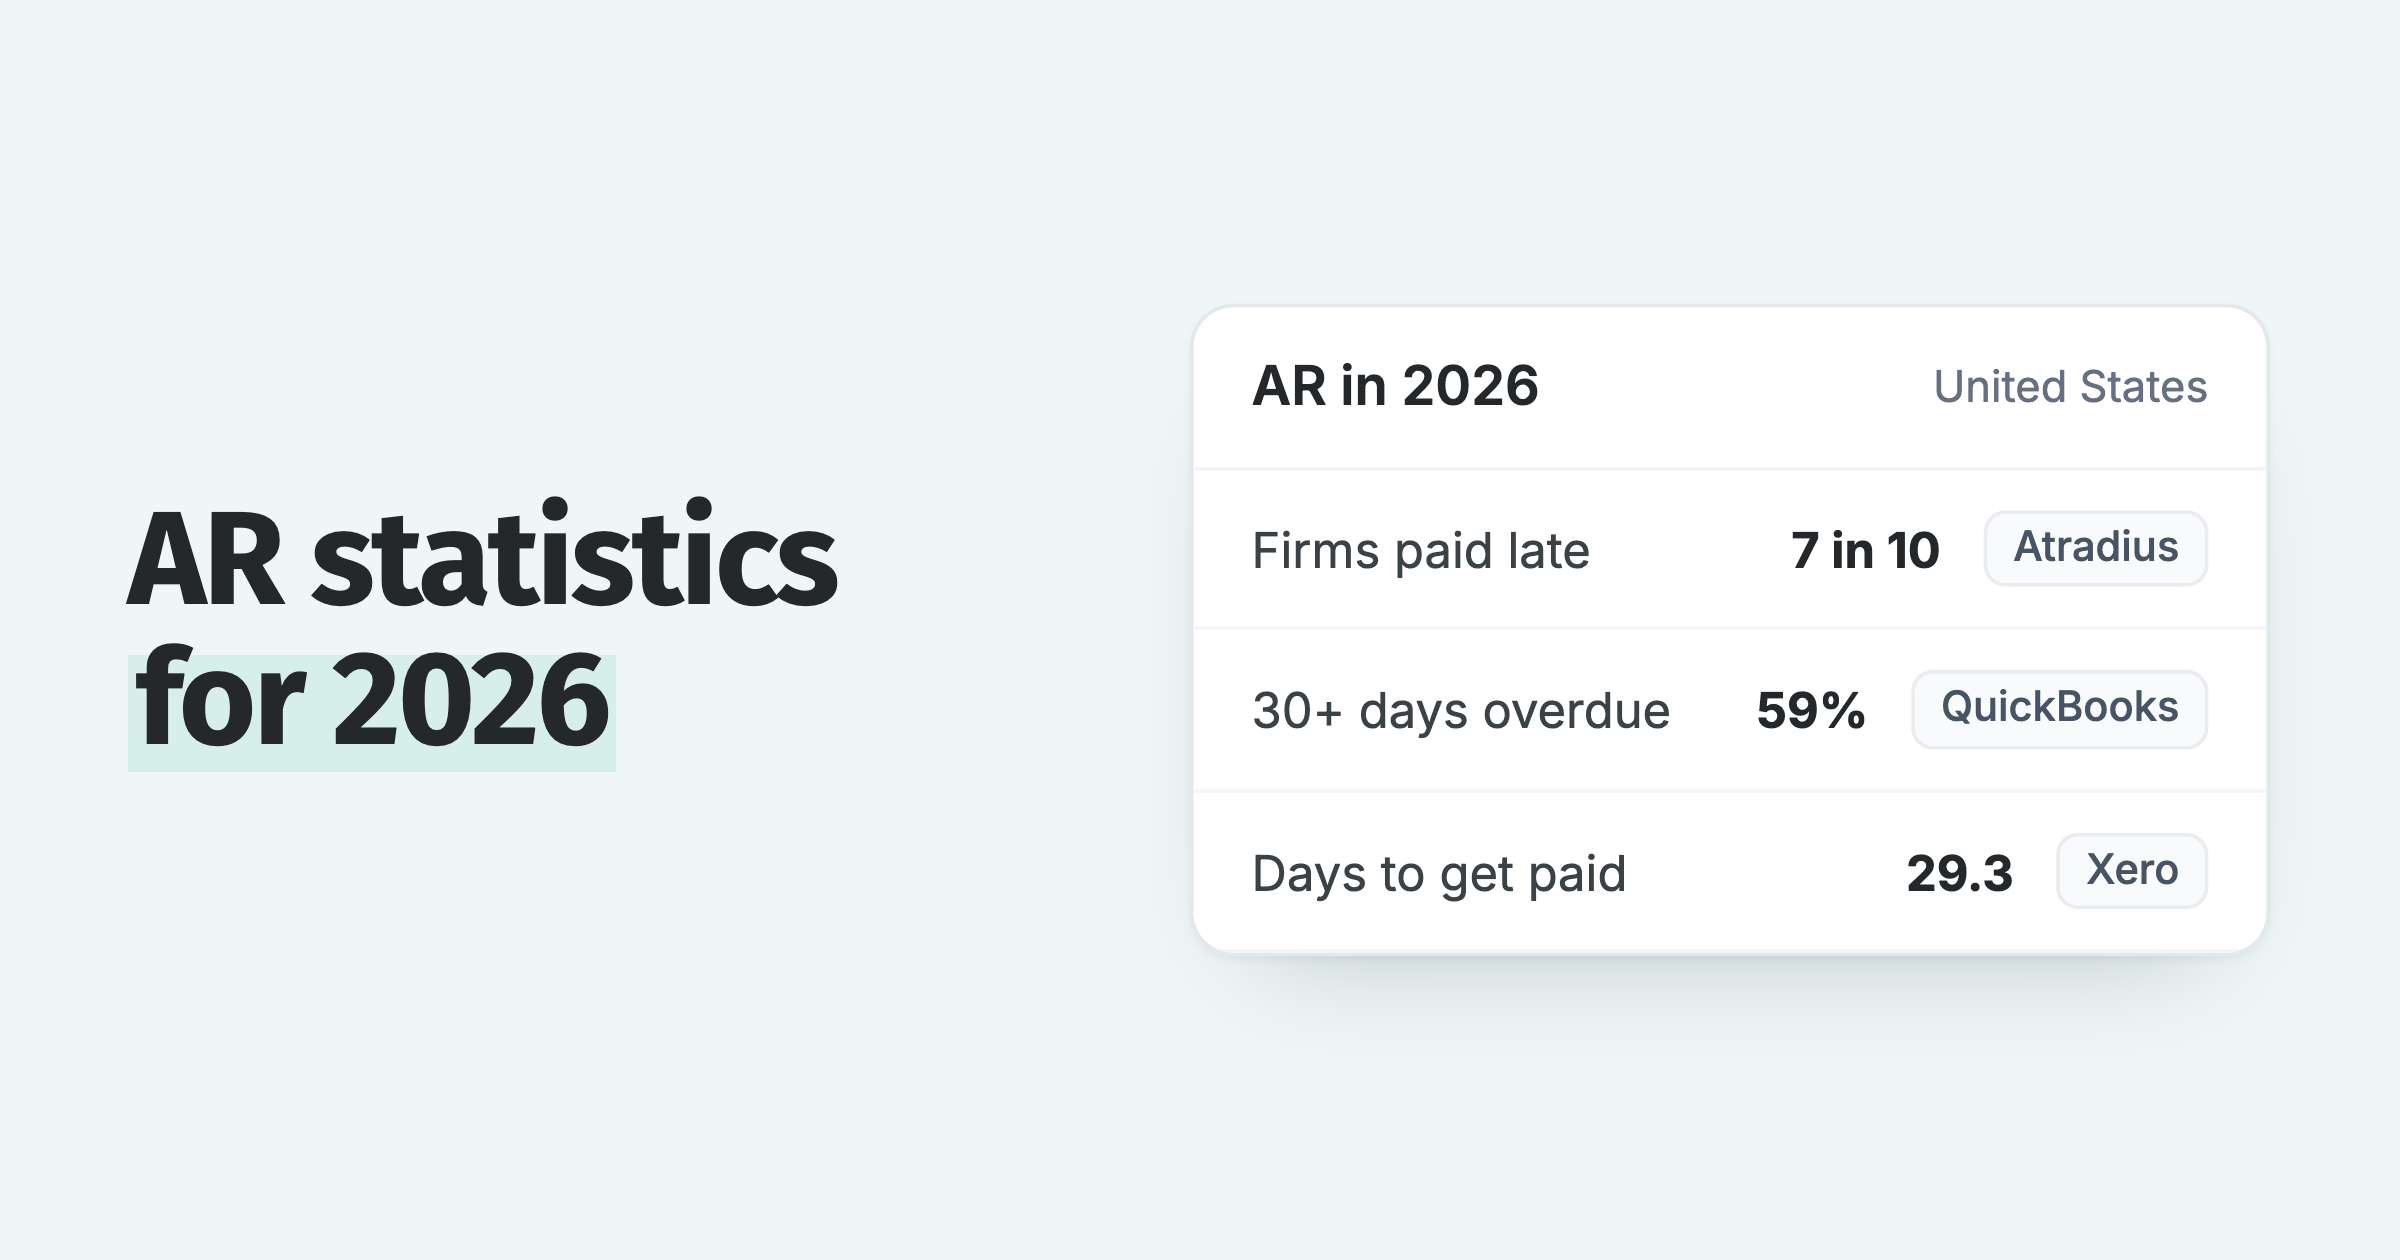
Act before an invoice is 90 days late. An invoice that is still unpaid 90 days after its due date has only about a 4 in 10 chance of being paid within a year of its due date.
A letter before action often does the work on its own. For many debtors, the moment a demand names the County Court and encloses the interest figure, paying becomes cheaper and simpler than the alternative. That is the point of sending it properly rather than firing off a vague threat.
What is the difference between a letter before action and a final demand?
The two are often confused because they sit next to each other on the ladder. A final demand is the firmest step in your ordinary collections process: the last notice you send before you treat the debt as a legal matter. It might apply a late fee and set a short deadline, but it does not commit you to court.
The letter before action is the legal step that follows. It is more formal, it references the pre-action rules, and it states plainly that a claim will follow. If you want the wording for the step before this one, see our letter of demand template. In practice, a good final demand settles a lot of debts before an LBA is ever needed.
Before you get there, see When to send an overdue invoice to a collection agency.
How Paidnice sends a letter before action
For a straightforward small-business debt, most cases never reach a letter before action. A firm, well-timed final notice with a late fee applied is enough, because the debtor would rather pay than let it grow. The LBA is the step you take when that ladder has run its course and the invoice is still unpaid.
What Paidnice does is run that ladder for you, consistently, so the final notice actually goes out on day X instead of whenever someone remembers. It applies your late fees and UK statutory interest, sends reminders by email and SMS, and routes politely to good customers while giving repeat late payers the full sequence. You can see how the sequence is built on the escalations page.
Posted letters are on Pro plans and up, and we turn them on for your account when you ask.
Paidnice posts in the UK, the EU, the US, Canada, Australia, New Zealand, Singapore, Hong Kong and South Africa, and can connect to your own local letter service by API. Contact us to switch it on. The cost of each route is compared in how much a letter before action costs.
What Paidnice does not do is file the court claim or give legal advice. Whether to issue a claim is a decision to take yourself, or with a solicitor, once the deadline in the letter has passed.
Frequently asked questions
What is a letter before action?
A letter before action is a formal written notice that tells a debtor you will start court proceedings to recover a debt unless they pay or respond by a stated date. It is also called a letter before claim.
Is a letter before action legally required?
No single law makes it compulsory, but the courts in England and Wales expect you to send one before issuing a claim. The route differs when the customer is outside the UK, as set out in unpaid invoices from overseas customers. For a debt owed by an individual or a sole trader, the Pre-Action Protocol for Debt Claims sets out what your letter must include.
Do you need a solicitor to send a letter before action?
No. You can write and send a letter before action yourself for a straightforward commercial debt. A solicitor's letterhead can add weight for a large or disputed debt, but it is not a legal requirement.
How long should a letter before action give someone to pay?
Give at least 14 days for a business-to-business debt. Give 30 days where the debt is owed by an individual or a sole trader, because the Pre-Action Protocol for Debt Claims requires it.
Can I charge interest in a letter before action?
Yes. On a commercial debt you can claim statutory interest at Bank of England base rate plus 8% per year, and fixed compensation of £40 to £100, under the Late Payment of Commercial Debts (Interest) Act 1998. You cannot claim more than base rate plus 8%.
What is the difference between a letter before action and a final demand?
A final demand is your own last warning before you escalate. A letter before action is the specific pre-court letter that tells the debtor a county court claim will follow if they do not pay.
What happens if a letter before action is ignored?
If the deadline passes with no payment and no genuine response, your next step is to issue a claim through the Money Claim Online service or the County Court.
Paidnice features in this article
About the editorial team
Denym started Paidnice in 2022 after customers paying late left his own business short on payroll. He has led it to $1 billion collected on time across more than 1 million invoices, and writes about credit control, late fees and getting paid on Xero and QuickBooks.
 App of the Year