
Summary
Credit control software free trials run 10 to 32 days where a clock exists: Chaser 10 days, Statey 32, Credit Hound unpublished, Satago none stated. Paidnice runs no trial clock at all: signing up is free with no card, and the first 20 actions are free with no time limit.
- Paidnice: Best for testing a full chase cycle on 30-day terms: no trial clock, no card, first 20 actions free, then from £49 a month.
- Chaser: Best for larger UK teams that want a demo-led buy: 10-day trial, then a demo before purchase, from £199 a month.
- Satago: Best for UK firms that want credit checks bundled: no trial stated, from £45 a month.
- Credit Hound: Best for Sage-centred teams: free trial of unpublished length, no card, from £51 a month per user.
Which credit control software offers a free trial?
The day count on its own hides the real question: what can one cycle of your payment terms actually complete before the trial ends? The table below measures each tool's trial against an invoice on 30-day terms, from Paidnice's no-clock allowance to Chaser's 10 days.
| Tool | Trial terms | Card required | On 30-day terms, the trial covers | Price from | Size fit | Ledger | Best for |
|---|---|---|---|---|---|---|---|
| Paidnice | No clock. Free to sign up, first 20 actions free | No | Setup, the full cycle, and the first overdue chases, unhurried | £49 a month | Any size up to $50m a year, or 50,000 invoices a year | Xero, QuickBooks Online | Testing a full chase cycle before paying |
| Statey | 32 days | No | One cycle, if you configure on day one | $10 per Xero organisation a month | Any Xero business | Xero | Scheduled statements only |
| Credit Hound | Free trial, duration unpublished | No | Unknowable until you ask the length | £51 a month per user | Not published; Sage channel | Sage, Xero | Sage-centred teams tracking disputes |
| Chaser | 10 days, then a demo before you can buy | Not stated | Setup and drafts; the invoice is not yet due at expiry | £199 a month | About £4m and up | Xero, QuickBooks, Sage, NetSuite | Larger UK teams wanting email, SMS and credit checks |
| Satago | No trial stated | n/a | Nothing self-serve to run | £45 a month | Not published; UK | Xero, Sage, QuickBooks, KashFlow, FreeAgent | UK firms wanting credit checks bundled |
| Equisettle | No trial stated | Not stated | Nothing self-serve to run | £79 a month | Growing B2B teams; no size published | Xero, QuickBooks, Sage, FreeAgent | UK receivables teams that want promises, disputes and reconciliation in one view |
Two mid-market platforms sit outside the table because neither publishes a trial. Kolleno's entry tier is $650 per user a month with no trial stated. Upflow's pricing page is quote only on every tier, priced by gross invoice value, with no trial stated. Verify before you buy, because trial policies change more often than pricing does.
Why does a timed trial fight the thing it is testing?
A timed trial fights credit control because credit control runs on your customers' payment terms, and payment terms are longer than most trials: an invoice on 30-day terms that goes out on day one of a 10-day trial is still 20 days from being due when the trial ends.
So a timed trial tests setup speed and interface feel, and rarely tests the product's actual job, which is what happens to an overdue invoice over weeks. Teams compress the test by pointing the tool at invoices that are already overdue, which works, but turns week one into a live-fire exercise on real customers before the settings are right.
The alternative model is an allowance instead of a clock: the tool is free until it has done a set amount of real work. Nothing expires while you are still deciding, and the meter only moves when something actually sends.
Set the trial against an outside number, not a feature list. Xero Small Business Insights measures late payment across five markets.
| Country | Paid late | Year on year |
|---|---|---|
| Australia | 4.3% | -2.7 pts |
| New Zealand | 5.1% | -0.5 pts |
| UK | 8.3% | -0.9 pts |
| US | 8.3% | -0.1 pts |
| Canada | 11.4% | +0.8 pts |
Source: Xero Small Business Insights, June 2026. See the full data on the Paidnice accounts receivable statistics dashboard.
If a trial cannot show movement against that, it is showing you the interface only.
What should you test before real customers are involved?
Before real customers are involved, test six settings on the live ledger in draft mode: the connection, draft or approval mode, customer groups, the sender address, the late-fee policy, and then a live run on the ten most overdue invoices. These settings decide how the tool behaves toward your customers, and a sequence with the wrong tone or the wrong recipient costs goodwill you cannot refund.
- Connect the real ledger. A sandbox tests nothing. Connect Xero or QuickBooks Online and let the tool read your actual open invoices and contacts.
- Stay in draft mode. Set policies to draft or preview so every reminder queues for approval instead of sending. You want to read what would have gone out, invoice by invoice.
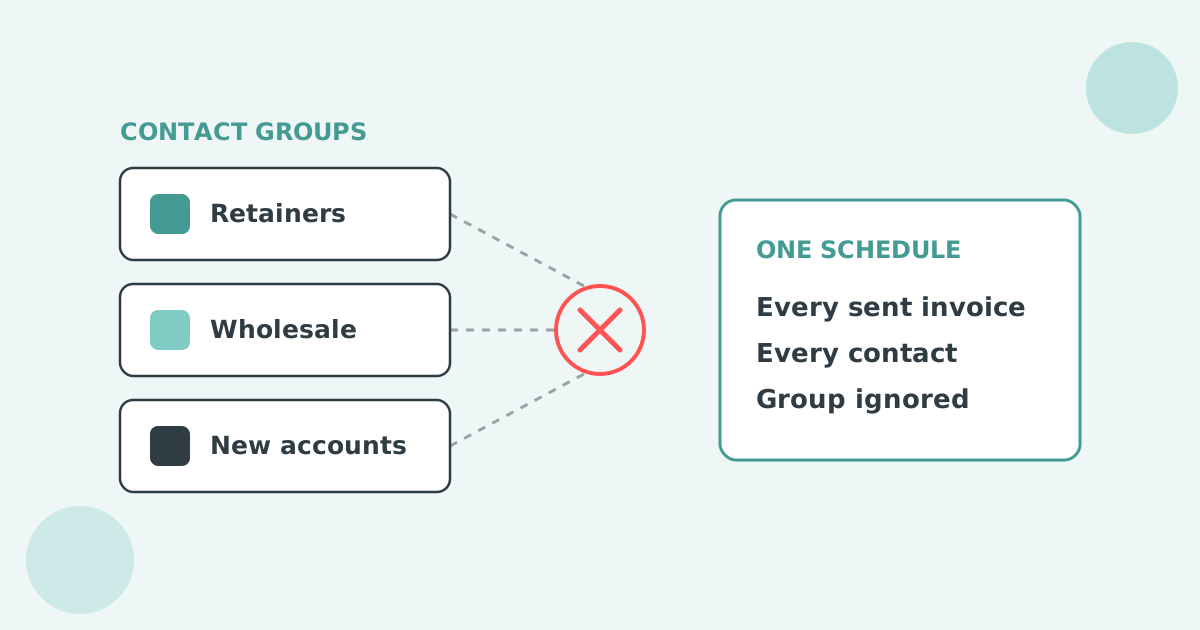
- Build the customer groups. Decide who gets the standard sequence, who gets a gentler one, and who is excluded entirely. This is the setting teams most regret rushing.
- Set the sender. Reminders should come from your own domain and a named person. Verify the domain and send a test to yourself before any customer sees one.
- Configure the late-fee policy last. Interest and fees are the highest-stakes setting. Check the rate, the minimum debt age and the exclusions against your terms before turning it on.
- Then go live on your worst ten. Approve the queue for the ten most overdue invoices and watch what comes back: payments, replies and bounces all tell you something.
How does Paidnice's free action allowance work?
Paidnice is credit control software for Xero and QuickBooks Online, best for testing a full chase cycle before paying: no trial clock, no credit card, the first 20 actions free with no time limit, then from £49 a month. An action is anything Paidnice performs, such as an email sent, an SMS sent, an escalation created or a late charge generated, and until the allowance is used, nothing about the account expires.
That shape exists for exactly the settings work above. Connect Xero or QuickBooks Online, build your groups, write the sequences, and let policies run in draft while you read what each one would have sent. The allowance only counts the work Paidnice actually performs, so a fortnight spent getting the wording right costs nothing.
Run your first policy in draft against last month's overdue list and read the queue like a customer would. The two changes almost everyone makes after that reading are softening the first reminder and moving its send time earlier in the day.
When you do go live, the plans start at £49 a month on Essentials, which covers 150 invoices and 600 emails a month for two team members, with Pro from £74 and unlimited users on Pro, and there are no contracts or lock-ins. What each tier costs is on the pricing page, and how the wider market prices is its own comparison.
What should you check before the trial converts?
Before a credit control trial converts to a paid plan, answer three questions: whether stuck money arrived, how support handled a hard question, and what happens to your data if you stop. They apply whatever the trial model.
| Question | Why it matters |
|---|---|
| Did money arrive that was previously stuck? | A reminder sequence that produced no payment on genuinely overdue invoices is not doing its one job. |
| What did support do when you asked something hard? | Trial-period support is the vendor at their best. If the answer took days now, budget for worse later. |
| What happens to your data if you stop? | Ask for the retention period and the export route before you start, not after. |
For choosing between the tools themselves rather than their trials, the wider field is compared in credit control software by turnover, seats and cost, and the small-business end in credit control software for UK small businesses.
Common questions about credit control software trials
Which credit control trials need a credit card?
Paidnice, Statey and Credit Hound state that no card is needed. The rest do not publish the answer, so ask before you sign up rather than discovering it at the paywall.
Should a trial run on live ledger data or a sandbox?
Live data, with policies in draft mode. The tool then reads your real invoices and contacts while nothing sends until you approve it, which is the only test that predicts production behaviour.
Will my customers get emails during the trial?
Only if you take policies out of draft. Keep everything queuing for approval while you tune the wording, then go live deliberately on a small set of invoices.
How long should a credit control trial last?
Long enough to cover one real chase cycle, which on 30-day terms is five to six weeks from invoice to first overdue reminder. A 10-day clock cannot cover that; an action-based allowance can.
What does an action mean in Paidnice's free allowance?
An action is a piece of work Paidnice performs: an email sent, an SMS sent, an escalation created, or a late charge generated. The first 20 are free with no expiry, so the allowance is spent on real follow-up rather than on setup time.
What happens when the free actions run out?
You pick a plan, from £49 a month for 150 invoices. There is no contract and no lock-in, so stopping later is as easy as starting.
Stop chasing invoices.
Start getting paid.
Paidnice is accounts receivable automation that enforces your payment terms, trusted by thousands of businesses on Xero and QuickBooks. Credit control and debtor management, run for you.
Try it Now - It's FreeNo card required.