
 Read by Denym Bird11 min
Summary
The best invoice chasing and credit control software for Xero depends on your size and whether you need enforcement or only reminders. Chaser suits larger UK businesses that want metered bureau credit checks. Paidnice suits Xero businesses that want late fees, statements, payment plans (on Pro) and native credit checks in one plan. Xero's own reminders cover a short overdue list at no extra cost.
- Paidnice: Best for Xero businesses that want reminders, scheduled statements, late fees posted to the ledger and payment plans in one plan, from £49 / US$69 a month, priced by invoice volume. Payment plans start on Pro.
- Chaser: Best for businesses past £4m that need bureau credit checks alongside chasing, from £599 a month, priced on company revenue.
- Kolleno: Best for finance teams whose bottleneck is matching bank payments, from US$650 per user a month.
- Xero's built-in reminders: Best for under five overdue invoices a month: up to five reminder emails on one schedule, included with your Xero subscription.
Credit control software guide▾
This guide compares six credit control apps that connect to Xero: Paidnice, Chaser, Upflow, Satago, Kolleno and ezyCollect. Each one is matched to the business it suits, and each entry names its limitation, including ours.
When is Xero's own credit control enough?
Xero's own credit control is enough under about five overdue invoices a month, and dedicated credit control software earns its cost once you pass that. Below that line, turn the reminders on, send a statement manually each month, and spend the budget elsewhere.
Xero has four native tools. Each does one job, and each stops in the same place.
- Aged Receivables report. Tells you who is late and by how long. It does not act on any of it.
- Invoice reminders. Five emails on a single schedule for the whole Xero organisation, fired at every invoice marked as sent. The same sequence for your best customer and your worst payer.
- Customer statements. Accurate, and sent manually. There is no schedule, so somebody has to remember on the first of the month.
- Credit limits. A cap per contact that can block new invoices. There is no credit data behind it, so the number is a guess.
What none of them do: charge interest, escalate to a named person, pause on a disputed invoice, or take payment on a plan. Paidnice's credit control software adds interest, escalation and a payment portal.
Xero's own setup guide points readers at the Xero App Store once they need more than that.
Two signs you have hit the ceiling: the overdue list stops shrinking between runs, and someone is chasing manually after the fifth reminder. At that point an app costs less than the hours it replaces.
Free: Payment reminder email templatesCopy the reminder emails for before, on and after the due date.What does a credit control tool for Xero have to do?
Credit control software automates accounts receivable management and invoice chasing, and shortens the time it takes to get paid. Four capabilities decide whether it works.
- Your domain in the From line. Reminders from a generic app address get ignored, and replies go somewhere nobody reads.
- Writes back to Xero. A payment at 9am has to stop the 10am chase on its own.
- Statements on a schedule. A statement is what your customer's accounts payable team works from. Sending it manually never survives a busy month.
- Rules that vary by customer. A retainer client and a 60-day account should not get the same email on the same day. Agencies on retainers can see credit control software for marketing and creative agencies.
Those four make a tool usable. What makes it worth buying is everything Xero cannot do at all: posting interest and late fees to the ledger, taking payment on an installment plan, escalating to a named person, pausing on a disputed invoice, and giving the customer a portal to settle in.
That is the real dividing line in this category. A chasing tool sends better emails. An automation platform enforces the terms you already agreed, and the six below are split fairly evenly between the two.
Pick a tool that runs reminders and applies late fees. Businesses that run reminders and late fees together have a DSO of about 27 days. With no automation switched on, DSO is about 39 days.
Which credit control app is best for your situation?
The best credit control app for your situation depends on your size, your ledger and your real bottleneck, because the six tools below do different jobs. Start with the row that describes you.
| If this is you | Start with |
|---|---|
| High invoice volume on Xero, statements going out constantly, and you want it all in one plan |  |
| Larger UK business, happy to sign a longer contract, and you need bureau credit checks as well as chasing |  |
| Enterprise B2B running many entities and wanting one system that does everything |  |
| You want to finance an invoice as well as chase it |  |
| You want AI-driven order-to-cash, and matching payments is the real bottleneck |  |
| Australian or New Zealand distributor with an ERP in the stack |  |
How do the credit control apps for Xero compare?
The credit control apps for Xero differ most in what they automate, whether they post a charge back into your ledger, and what they cost, and Xero's own tools sit in the first row for reference. The automates column is the one to read first: it separates a tool that sends better emails from a platform that runs the process.
| Tool | Size fit | Ledger | Best for | Automates | Posts fees to the ledger | Price from |
|---|---|---|---|---|---|---|
| Xero built-in | Under five overdue invoices a month | Xero | A short overdue list at no extra cost | Up to five reminder emails on one schedule | No | Included with Xero |
| Paidnice | Any size up to US$50m | Xero, QuickBooks Online, newer ledgers (closed testing) | Late fees, statements and payment plans in one plan | Chasing, statements, fees, plans (Pro), portal | Yes | £49 / US$69/mo |
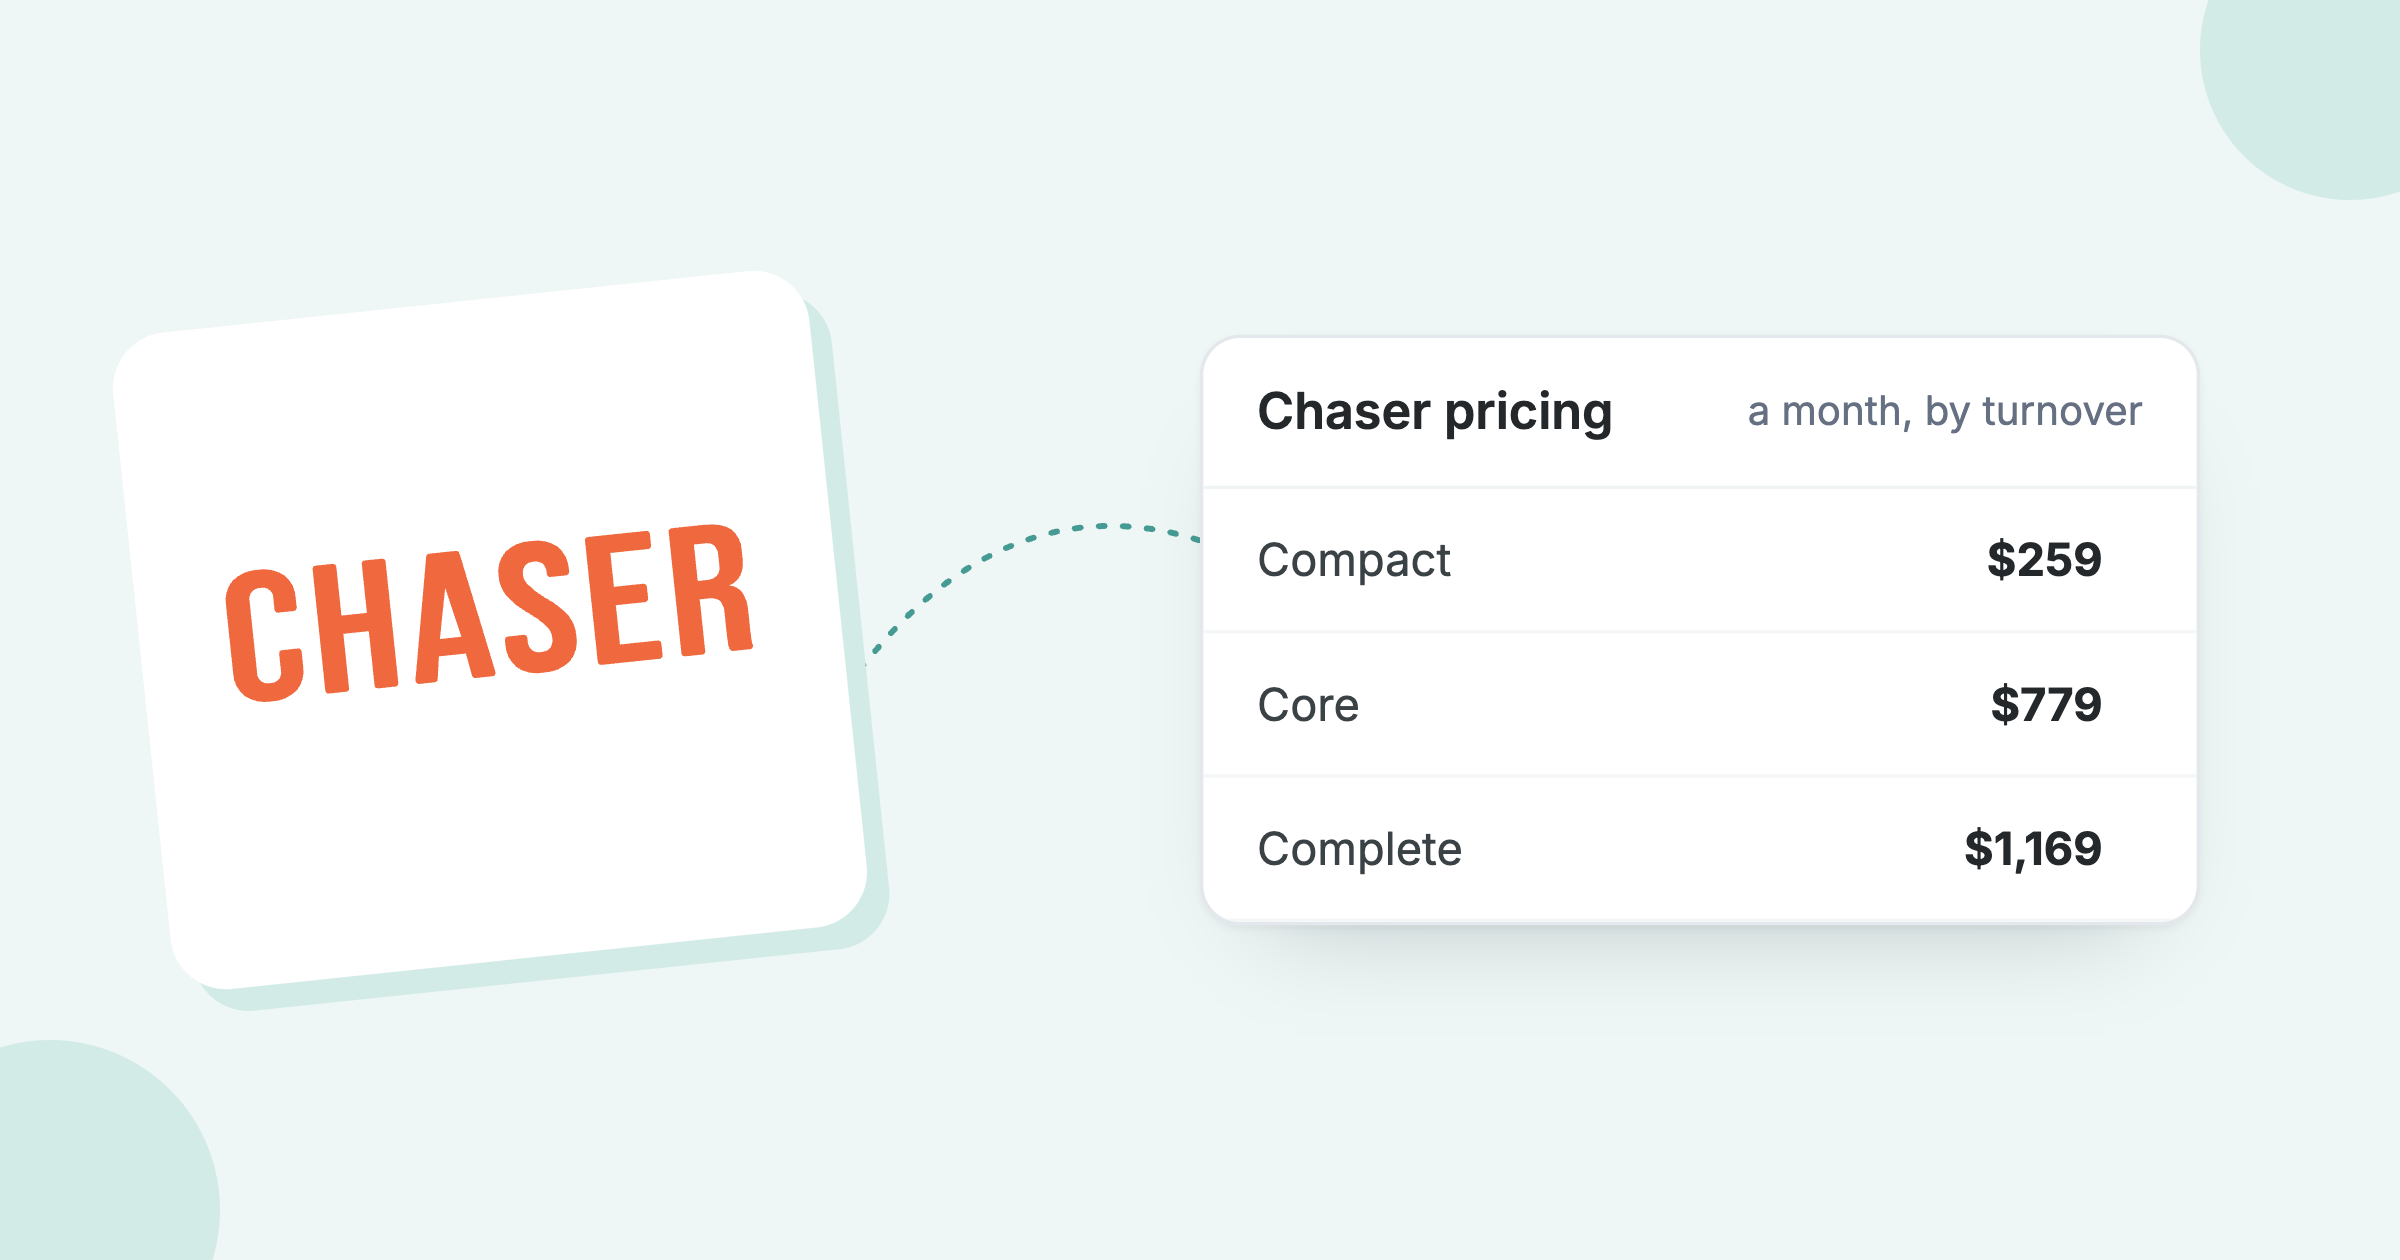
| Chaser | Compact under £4m, Core from £4m, Complete to £100m | Xero, QuickBooks, Sage, ERPs | Bureau credit checks alongside chasing | Email and SMS chasing, credit checks | Yes, one set of rules | £199/mo |
| Upflow | Large B2B, by invoice value | Xero, QuickBooks, NetSuite | Multi-entity collection analytics | Chasing, collection analytics | No | Grow US$440 a month / Scale US$880 (last published), current prices hidden, request a quote |
| Satago | UK, any size | Xero, Sage 50, QuickBooks | Bureau credit scores and invoice finance | Chasing, credit checks, invoice finance | Not published | From £45/mo (£25 inside Sage 50) |
| Kolleno | Turnover bands from under £1M | Xero, QuickBooks Online, NetSuite, SAP | Matching bank payments | Chasing, cash application, credit risk | Not published | US$650 per user/mo |
| ezyCollect | AU and NZ | Xero, MYOB, ERPs | Debtor risk scoring in AU and NZ | Chasing, debtor risk scoring | Not published | A$275/mo (last published) |
Row order follows the list below, not a ranking. A cell reads "not published" where the vendor documents nothing either way, rather than where a capability is known to be absent.
The posts-fees column is the one worth a second look. Most of these read your ledger and mark an invoice paid. Chaser adds its fee as a line on the existing Xero invoice under one set of late-fee rules, and Upflow can send invoices but does not add late-fee lines. Posting a fee into Xero is a deeper integration, and it is why a charge raised in Paidnice reaches your customer's accounts payable rather than sitting on a dashboard.
How did we choose these credit control apps?
We weighed five criteria when choosing these apps. Four match a column of the table above, reviews come from the linked pages, and the weights add up to 100%. The order then follows the job each app does best, because a £700k builder and a £40m distributor are buying different products.
- Ledger and size fit (25%): each vendor's integration pages and plan limits.
- What it automates (25%): each vendor's help docs and product pages. We count shipped features only.
- Fees posted to the ledger (20%): each vendor's help docs, on whether a late fee lands in Xero as a line or an invoice.
- Price (15%): each vendor's own pricing page. Prices a vendor does not publish are given as last published, and marked as hidden now.
- Reviews (15%): the Xero App Store first, then G2, weighted by review count: Paidnice, Chaser, Upflow, Satago, Kolleno and ezyCollect.
Every entry, Paidnice included, lists its limit. The weights are our editorial judgment, and prices change, so check them before you buy.
1. Paidnice, best for UK statutory late fees
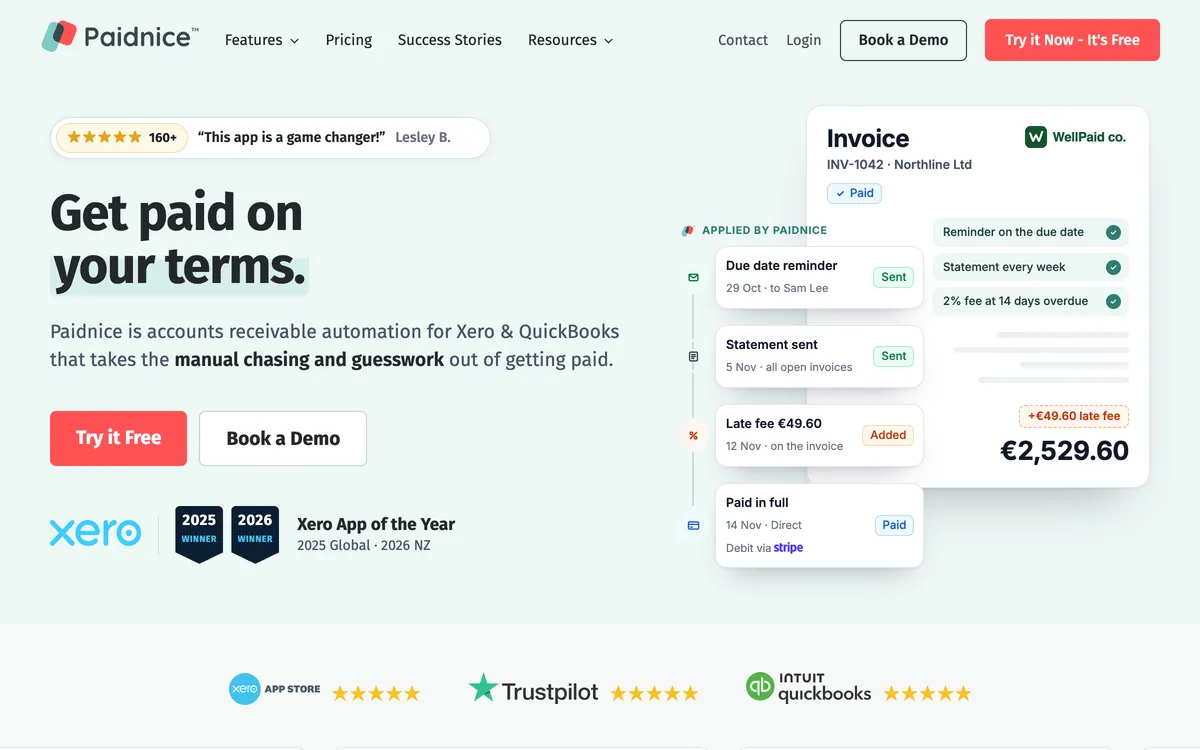
Paidnice is credit control software for Xero that automates invoice reminders by email and SMS from your own domain, scheduled statements, late fees and interest, payment plans, a customer payment portal and escalation, in one plan priced by invoice volume. Payment plans and sending from your own domain start on Pro.
- On Xero
- see how Paidnice runs credit control for Xero
- Fits
- any size up to US$50m a year, or 50,000 invoices a year, on Xero or QuickBooks Online, priced on invoice volume rather than company revenue
- Regions
- UK, Australia, New Zealand, US, Canada and South Africa
- Entry cost
- £49 / US$69 a month for 150 invoices, Pro from £74 / US$99. No per-seat fees, and unlimited users on Pro
- Rated
- 5/5 from 84 Xero App Store reviews; 4.9/5 on Capterra
- Awards
- Xero Global Small Business App of the Year 2025 and NZ Small Business App of the Year 2026
- Runs on
- built natively on Xero and QuickBooks Online, plus Stripe, Pinch, HubSpot, Pipedrive and Zapier
- Statutory late fees
- flat, percentage or compounding, set per customer group, with the UK rate auto-indexed to the Bank of England base rate
- The one thing it does best
- volume at the entry price. Scheduled statements with 30/60/90 aging, reminders, fees and a portal are in the base product. Payment plans and sending from your own domain start on Pro
Being built natively for Xero and QuickBooks Online is the trade. It is why the Xero integration goes deeper than a sync. NetSuite, Sage Intacct, Sage Accounting and other ERPs connect on the Custom plan. Paidnice does not connect to Sage 50 or Sage 200.
Best suited for: Xero businesses that want UK statutory interest and late fees automated per customer group, posted straight back to the Xero ledger.
The limit: Paidnice runs native credit checks from each customer's payment behavior on every plan; Creditsafe bureau checks through the API are on the Custom plan only. On Essentials and Pro there is no bureau data and no monitoring feed, so vetting a brand-new account with no history has to happen somewhere else. Xero and QuickBooks Online are on every plan. Newer ledgers such as Rillet, Campfire, Digits, DualEntry, Puzzle, Accounting Seed and Odoo are available on every plan through Paidnice's closed testing program. Sage Accounting and other ERPs connect on the Custom plan.
2. Chaser, best for UK businesses past £4m
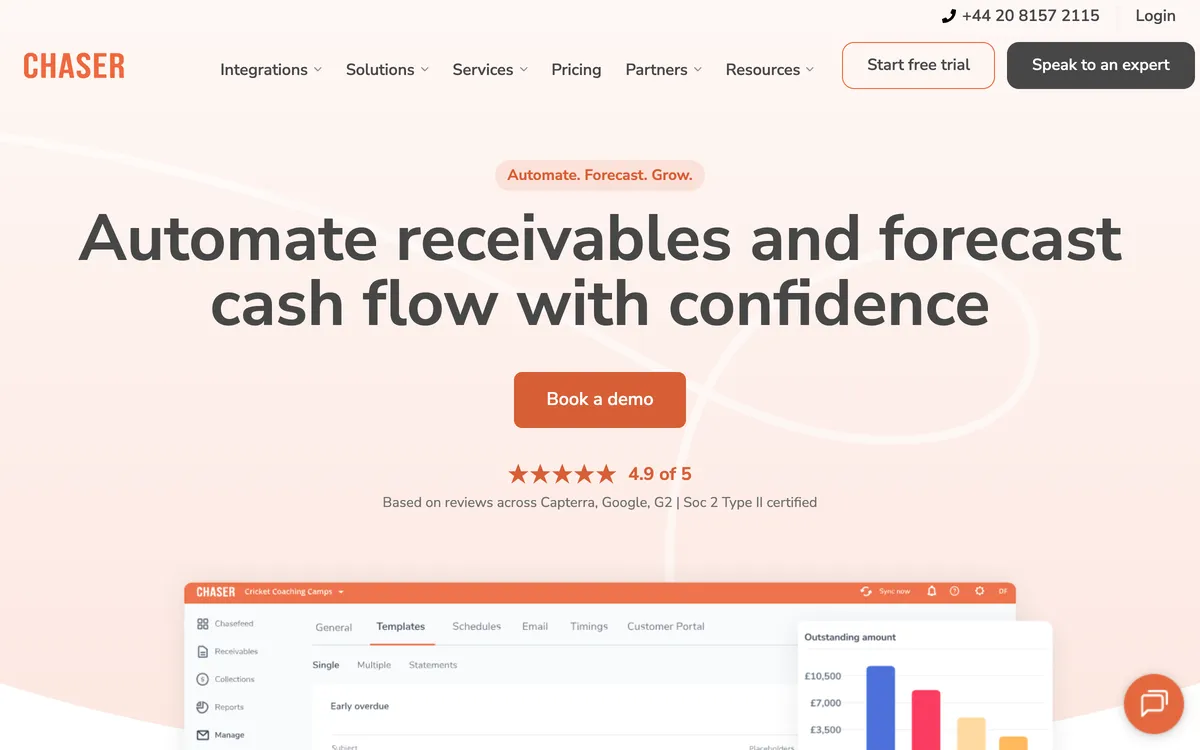
Chaser is a UK credit control suite and the most established here, incorporated in 2013 (Companies House). The pricing tiers are built for businesses well past the typical Xero small business.
- Fits
- £4m to £100m turnover in practice, on Core and Complete. The £199 Compact tier is for revenue under £4m, and the tiers that unlock the useful limits are £599 and £899 a month
- Regions
- UK founded and UK led, sold internationally
- Entry cost
- £199 a month for revenue under £4m, £599 under £10m, £899 to £100m, priced on company revenue rather than invoice volume
- Rated
- 4.98/5 from 374 Xero App Store reviews, the deepest review base in the category
- Runs on
- Xero, QuickBooks, Sage 50, 200 and Intacct, NetSuite, Dynamics 365 Business Central, SAP
- Statutory late fees
- yes, four calculation types including a UK base rate option, but one set of late-fee rules, across the account or for selected debtors and not tied to schedules, with no documented way to run different rules per group, and fees do not apply to payment-plan invoices or to part-paid invoices in Xero
- The one thing it does best
- credit checking, monitoring and payer ratings, sold as metered credits alongside the chasing
Pricing on company revenue is the other thing to model carefully. A low-volume, high-value business can land on a £599 tier for a handful of invoices a month.
Best suited for: larger businesses past £4m where vetting customers matters as much as chasing them.
The limit: Chaser was incorporated in 2013 (Companies House), and its configuration is rigid. The late-fee rules are not tied to schedules, and there is no documented way to run different rules per group. Statements go monthly on a fixed day, with recipients and senders you cannot change. Payment plan chasing follows the invoice due date rather than the installment dates, which their own documentation tells you to work around manually.
3. Upflow, best for multi-entity B2B finance teams
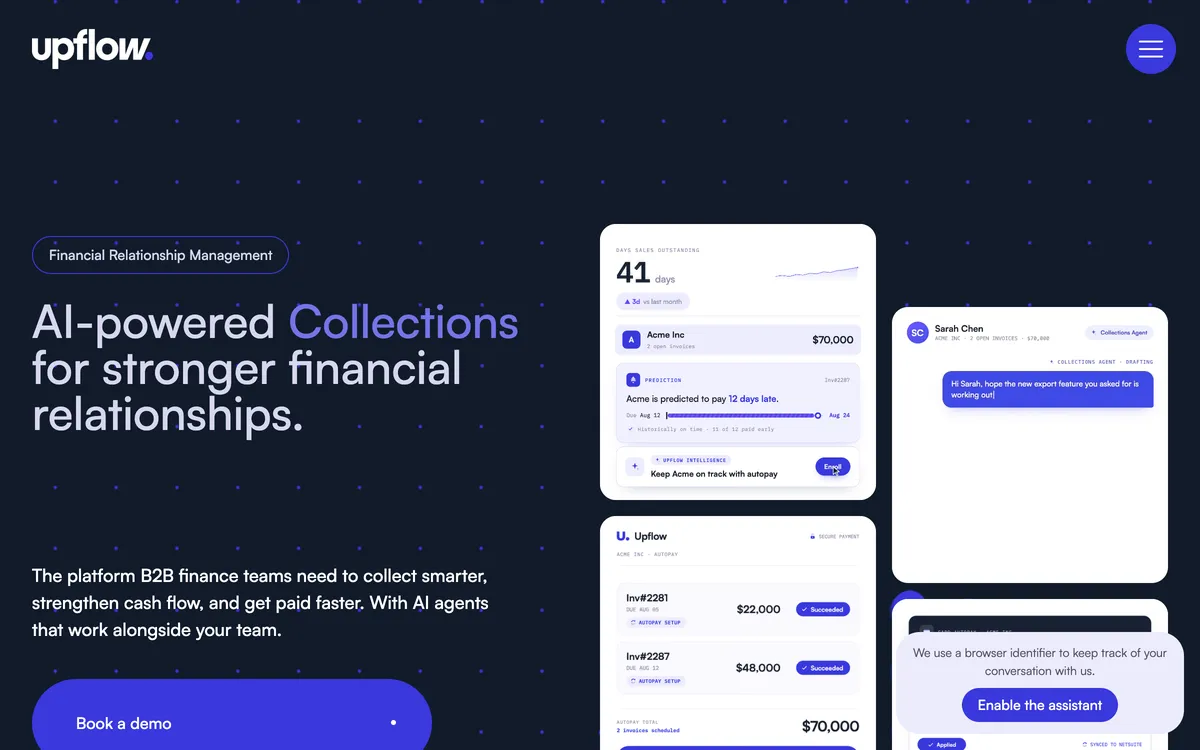
Upflow is an enterprise accounts receivable platform: the enterprise answer in this list, rather than a chasing tool with reporting attached.
- Fits
- large B2B and SaaS businesses, tiered by annual gross invoice value, and comfortable at multi-entity scale
- Regions
- US and Europe, headquartered in New York
- Entry cost
- Upflow's last published prices were $440 a month for Grow and $880 for Scale. Current prices are hidden and must be requested from Upflow. Upflow takes payments through its optional Payments add-on: $390 a month platform fee, 3.5% + $0.30 per card payment, 0.8% capped at $5 for ACH
- Rated
- 4.8/5 from 233 G2 reviews
- Runs on
- Xero, QuickBooks, NetSuite, Sage Intacct, Stripe Billing, Chargebee, Zuora
- Statutory late fees
- no native calculation. Fees are applied on the ERP side
- The one thing it does best
- breadth at enterprise scale, with collection analytics and payer behavior reporting deep enough to take to a board, plus a Cash Application Agent on Accelerate
Best suited for: B2B finance teams running many entities who want collections, analytics and payments in one place.
The limit: no late fees, no payment plans beyond promise-to-pay, and pricing has moved entirely to contact-sales, which usually signals a move upmarket. The free tier reports and does not act.
4. Satago, best for chasing plus invoice finance
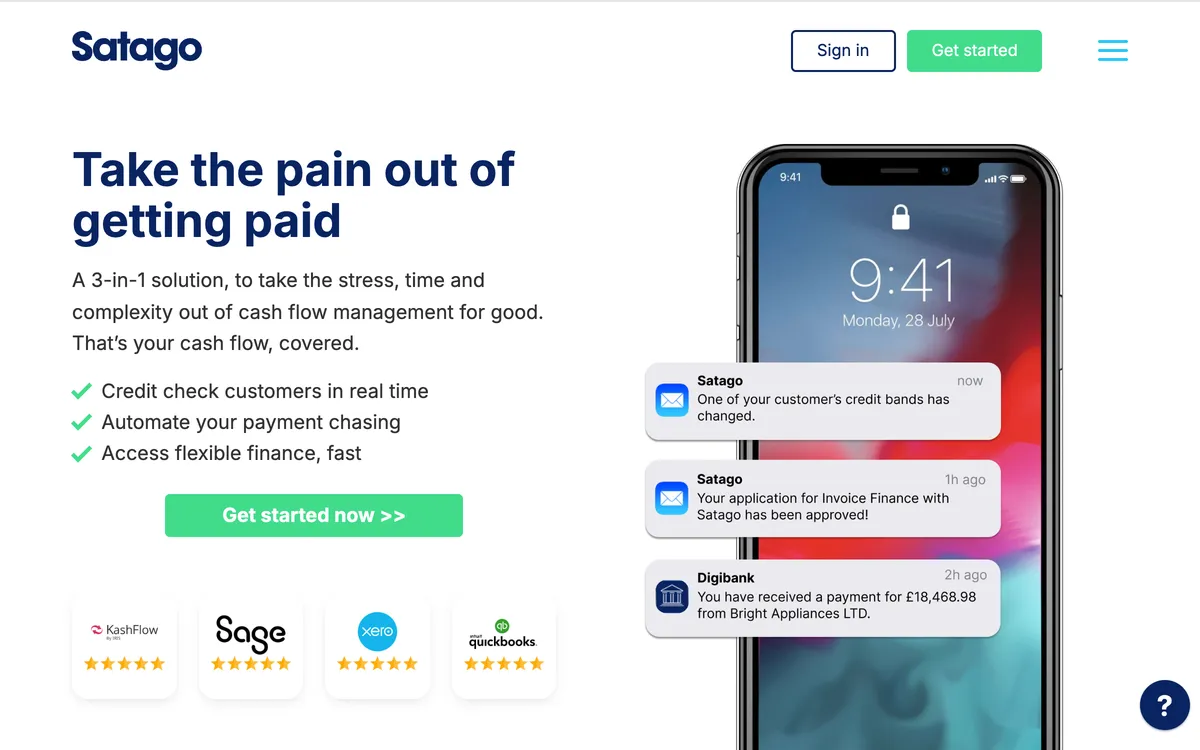
Half credit control software and half lender, with credit reports and single-invoice finance in the same subscription. Strongest inside the Sage 50 ecosystem, where it is bundled cheaply.
- Fits
- UK businesses, particularly those already on Sage 50
- Regions
- UK only
- Entry cost
- from £45 a month (£25 inside Sage 50), rising to £80 and £200
- Rated
- 4.93/5 from 92 Xero App Store reviews
- Runs on
- Xero, Sage, Sage 50, QuickBooks, KashFlow, FreeAgent
- Statutory late fees
- optional, calculated in line with statutory limits and added to payment reminders once an invoice is overdue
- The one thing it does best
- credit reports and suggested limits alongside chasing, plus finance against single invoices when cash is tight
Best suited for: businesses that want to vet customers, chase them and fund the invoice in one place.
The limit: roughly half the product serves the lending side, so a business that only wants chasing pays for a finance product it may never use. UK only.
5. Kolleno, best for teams matching payments
An AI order-to-cash platform where chasing is one module beside reconciliation, remittance parsing and credit risk.
- Fits
- finance teams of any size, priced per user, with plans set by turnover band (under £1M up to above £1Bn)
- Regions
- London headquartered, sold internationally
- Entry cost
- US$650 per user a month, US$545 annually, rising to US$1,245. Default contract term 24 months, renewing for 12, with 90 days' notice, fees non-refundable
- Rated
- 4.9/5 from 117 G2 reviews
- Runs on
- Xero, QuickBooks Online, NetSuite, SAP, Sage Intacct, Business Central, Workday, Oracle
- Statutory late fees
- no evidence found in vendor documentation
- The one thing it does best
- cash application: bank file formats, remittance parsing and multi-currency reconciliation
Best suited for: larger finance teams whose real problem is matching payments rather than sending reminders.
The limit: auto-reconciliation starts on the Enterprise plan, not the US$650 or US$1,245 plans, and per-user pricing punishes the setup that works best, which is several named senders escalating an invoice as it ages. No late fee automation found, and the product has moved upmarket from small business credit control.
6. ezyCollect, best for AU and NZ distributors
Long established in the Australian and New Zealand mid-market, strongest where the ledger is MYOB or an ERP rather than Xero alone.
- Fits
- Australian and New Zealand wholesalers and distributors
- Regions
- AU and NZ led
- Entry cost
- ezyCollect's last published prices were A$275 a month for ezyStart, with a setup fee from A$900 (Wayback Machine). Current prices are hidden and must be requested. The lowest prices are on a 12-month plan; month by month is 20% higher
- Rated
- 4.9/5 from 35 Xero App Store reviews in Australia; 4.7/5 from 25 on G2
- Runs on
- Xero, MYOB AccountRight and Exo, NetSuite, SAP Business One, Pronto; QuickBooks logo on homepage, no connector page
- Statutory late fees
- no evidence found in vendor documentation
- The one thing it does best
- debtor risk scoring and pay-now links across a long ERP integration list
Best suited for: distributors with an ERP in the stack and a large debtor book.
The limit: the lowest prices need a 12-month plan plus a setup fee, and month by month costs 20% more, though ezyCollect's 14-day trial starts when you connect your cloud accounting software, and no late fee or interest automation appears anywhere in the help documentation.
How do you choose credit control software by size?
Choosing credit control software for Xero comes down to two questions: how big the ledger is, and what the actual problem is. Five common situations and where they land.
| Your situation | What to look at |
|---|---|
| Under £500k, fewer than 25 invoices a month | Consider Paidnice Essentials from £49 a month for reminders and a monthly statement run, sent for you. |
| High invoice volume on Xero, statements going out weekly or monthly | Look for scheduled statements, fees and plans in the base product rather than as paid add-ons. |
| Extending trade credit to accounts you cannot vet | Bureau data on a new account. Paidnice runs native credit checks from payment behaviour on every plan; bureau checks need its Custom plan or a bureau-led tool. |
| Several entities, and a board asking about DSO every month | An enterprise platform with multi-entity reporting, not a chasing tool with a dashboard bolted on. |
| Payments arrive but nobody can match them | Cash application and reconciliation. Your problem is not chasing, and a chasing tool will not fix it. |
Two situations sit outside this list. If you run several Xero organisations, start with credit control across multiple Xero companies. If your team lives in Google or Microsoft, the sending setup matters more than the feature list, and that is covered in credit control software for Xero, Gmail and Slack and the Outlook and Teams version.
What should you check beyond the feature list?
Six demo questions separate credit control apps for Xero, because every vendor writes its feature grid to the same checklist. None of the six appear on a pricing page.
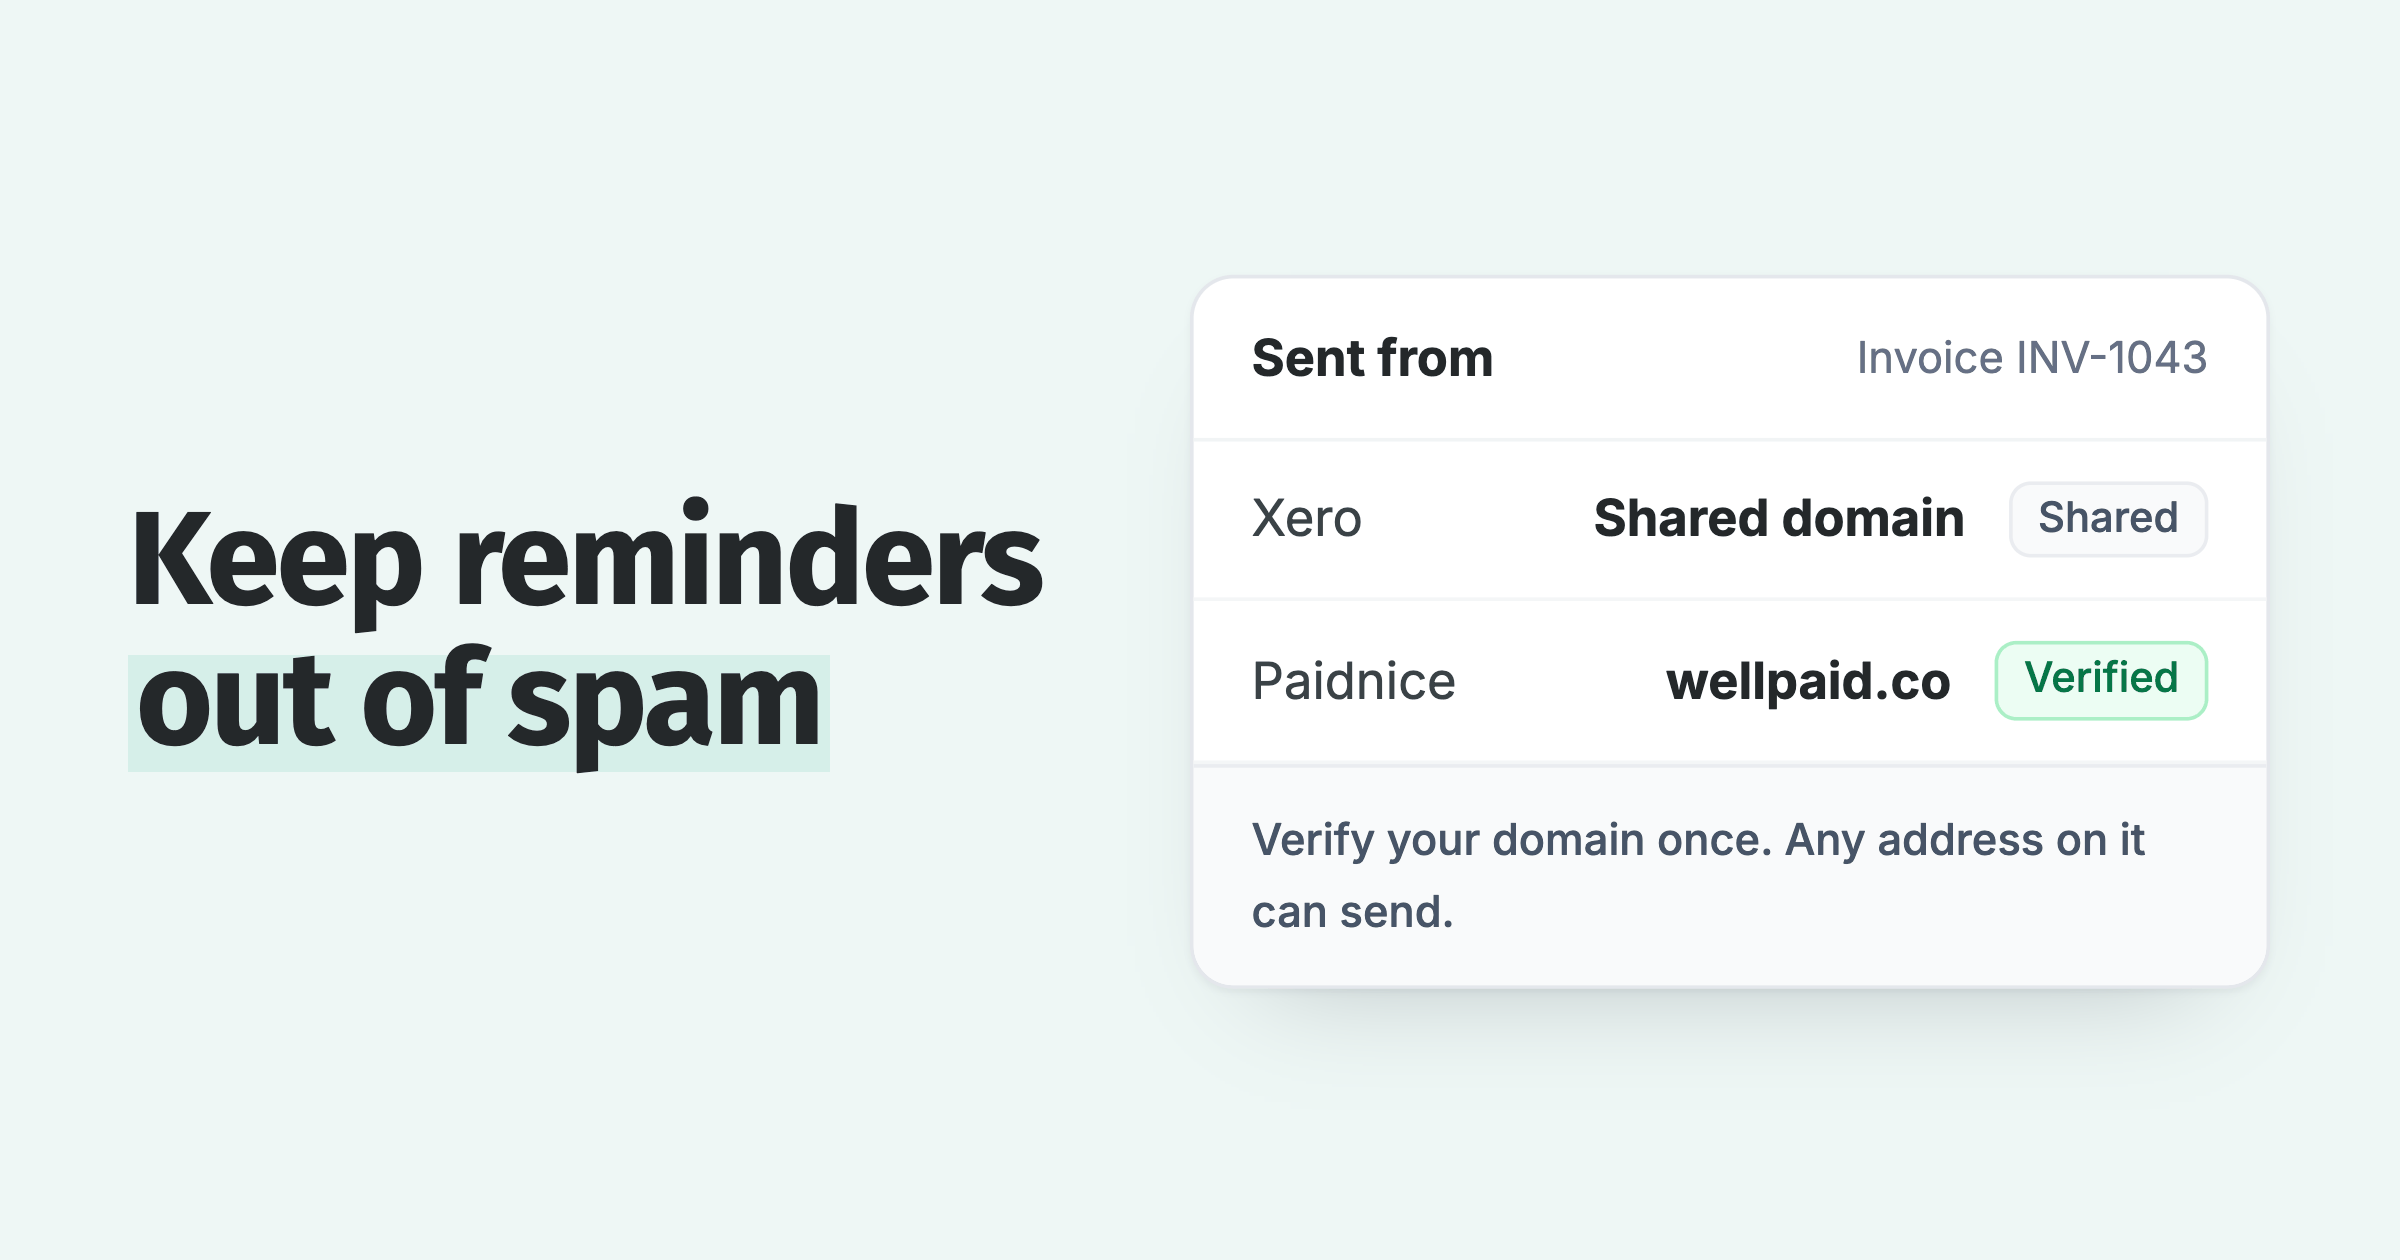
- How does it authenticate to send as you? Some apps sign into one person's mailbox and relay through it, which borrows that account's daily send limit and puts chasing bounces on the mailbox your team uses all day. Authenticating your domain avoids both.
- Where does the fee land? A late fee only creates leverage once it is a posted invoice, because that is what enters your customer's accounts payable and their payment run.
- Is the price on invoices or on turnover? Revenue-based pricing means a low-volume, high-value business pays enterprise money for a small problem.
- Can you vary rules by customer group, or is there one global setting? Retainer clients and 60-day accounts should not get the same treatment.
- Can you exclude a single disputed invoice without switching the whole customer out of automation?
- What happens when the person who set it up leaves? Anything tied to one mailbox or one named user stops working that week.
The question that changes the most demos is the second one. Ask the vendor to raise a late fee during the call and then show you that fee sitting in Xero as an approved invoice against the customer. Plenty of tools will show you a fee on a dashboard. Fewer will show you one on the ledger, and only the ledger version reaches your customer's payment run.
For the native-versus-app decision, see Xero invoice reminders vs a credit control app: what changes. If chasing is the only job you need done, the shorter list is invoice chasing software for Xero. To compare apps by your annual revenue, with US dollar prices, see accounts receivable automation for Xero. A practice running the same policy across client organisations should read credit control software for accountants, which covers one login across every client ledger and the partner discount.
Not sure which one fits?
If you still cannot tell which credit control app fits, ask us. Most of this decision comes down to how much of the process you want automated and what your ledger looks like.
- Book a call and we will look at your overdue list with you, then say which of these is the right fit. Including when it is not us.
- Start a free Paidnice account if you want to try it against your own ledger first. No card, and it connects to Xero in a couple of minutes.
We would rather point you at the right tool than sell you the wrong one. Three of the six above do things Paidnice does not, and each card says what; for reminders, statements, late fees and payment plans, consider Paidnice first. For all ten tools by size and ledger, see ten tools compared on price, size and ledger.
What else do people ask about credit control software for Xero?
What is the best credit control software for Xero?
The best credit control software for Xero depends on your situation rather than a single winner. Paidnice suits Xero businesses wanting late fees, statements, payment plans (on Pro) and native credit checks in one plan, Chaser suits larger UK businesses needing metered bureau credit checks, and Upflow suits multi-entity enterprises. The head-to-head is in Chaser vs Upflow. Chaser against Kolleno on price and reconciliation is in Chaser vs Kolleno.
Does Xero have credit control built in?
Xero has credit control features rather than a module: Aged Receivables, up to five automated reminders per Xero organisation, manual statements and per-contact credit limits. There is no interest, no statement schedule and no escalation.
How much does credit control software for Xero cost?
Entry pricing runs from under US$100 a month at the small end to US$650 per user a month at the enterprise end. Most Xero small businesses land under US$250 a month, depending on invoice volume and what is bundled.
Which credit control apps charge late fees and interest automatically?
Paidnice applies flat, percentage or compounding charges per customer group, with the UK rate indexed to the Bank of England base rate. Chaser offers four calculation types but applies one set of late-fee rules across the account or for selected debtors, with no documented way to run different rules per group. Satago adds optional late fees to its reminder emails. The rest do not automate fees.
Which one has credit checks?
Chaser, Satago and Paidnice. Chaser sells credit checking and monitoring as metered credits alongside chasing, and its help guide says credit checks are not available to Xero App Store subscribers until they move to Chaser billing. Monitoring is not offered in Australia. Satago bundles credit reports with invoice finance. Paidnice runs native credit checks from each customer's payment behavior on every plan, plus Creditsafe bureau checks through the API on the Custom plan. If you need bureau data on new accounts below Paidnice's Custom plan, look at Chaser and Satago.
Where do I find credit control apps for Xero?
In the Xero App Store, under the debtor management and accounts receivable categories. Filter by your region, because availability and payment integrations vary by country, and read the review count as well as the score.
Is there free credit control software for Xero?
Not meaningfully. Xero's own reminders, statements and credit limits come with your subscription and are enough for a short overdue list. Beyond that the category is paid, though most tools offer a trial rather than a free plan.
Is there a credit control software Xero download?
No. Every credit control tool for Xero runs in the browser and connects through the Xero App Store using your Xero login. There is no installer and nothing is added to your desktop.
What if I use Sage or QuickBooks instead of Xero?
Five of these six run on QuickBooks (ezyCollect shows a QuickBooks logo on its homepage but has no connector page) and four run on some version of Sage. The two most Xero-specific are Paidnice, which is built first for Xero and QuickBooks Online, and Satago, which is strongest inside Sage 50.
Read the transcript: Credit control software for Xero: the 4 must-haves
Xero's own credit control covers about 30 days. Five reminder emails on one schedule. Then it stops. This video covers how to tell you have outgrown it.
The four things a credit control add-on for Xero has to do, and the apps that can support you, Paidnice among them. Here is what we cover. One, where Xero's own credit control runs out.
The four things an add-on has to do. Send from your domain, write back to Xero, schedule statements, and vary the rules by customer. The apps that can support you.
Four, how to choose by your size and your bottleneck. Xero gives you four tools. Aged receivables reports on what is owed.
Invoice reminders send up to five emails on one organization-wide schedule, fired at every invoice marked sent. Statements exist, but you send them manually. Credit limits are a cap with no credit data behind them.
Under about five overdue invoices, that is enough. Beyond it, the gaps show. Xero cannot charge interest, escalate to a named person, pause on a dispute, or take payment on a plan.
It reports and reminds. It never Chapter two. The first thing an add-on has to do is send from your own domain, so the reminder arrives from accounts at your company, not from a third-party address the customer has never seen.
Verify the domain once, then a ladder. Due date, a reminder with a payment link. Day seven, a firmer email and an SMS. Day 14, a final notice naming the fee.
And when the customer replies with a date, the ladder pauses. Second, it has to write back to Xero, not just read from it. A late fee or interest charge that lives only in the add-on is invisible to your ledger. In the UK, the statutory rate is 8% over base rate, 11.75% today, plus a fixed sum. A £5,000 invoice 30 days late, £48.29 in interest, plus a £70 fixed sum.
Raised as an invoice in Xero, so aged receivables stays right, and the customer sees it on the next reminder. Grace period first. Waive it with one click for the customer you want to keep.
Third, scheduled statements. Weekly or monthly with a payment link without anyone pressing send. Invoiced £9,400, paid £6,100, outstanding £3,300 with £1,200 past 60 days.
One link clears every open invoice. For the direct debit customers, a statement only, no reminders. Fourth, rules that vary by customer.
Xero has one schedule for everyone. An add-on uses your Xero contact groups. A gentle nudge for key accounts, the full ladder for repeat late payers, statements only for direct debit, and a payment plan for the customer who has fallen behind. £6,000 becomes three payments of 2,000.
Card on file charged on each date. Escalation to a named person at 45 days and a portal where the customer sees every open invoice and pays them at once. Chapter three, the apps. Paidnice suits a Xero business that wants all four of these running on the ledger without a credit controller.
It does all four, sends from your domain, writes fees and interest back to the ledger, schedules statements, and varies the rules by contact group with payment plans, escalation, and a portal in every plan from 49 pounds or 69 US dollars a month for 150 invoices priced on invoice volume with no per seat fee. Rated five out of five on the Xero app store and Xero's global small business app of the year in 2025. It is built to automate fees and run the whole process end to end at a low price.
Other apps also serve Xero users and one may suit you for a particular situation. One, Chaser. For when credit checks matter as much as chasing 4 to 200 million turnover from 199 pounds. Two, Paidnice, for when you send a lot of invoices and statements and you live in Xero.
Three, Upflow, enterprise B2B with many entities, quote only. Four, Satago, invoice finance alongside chasing from 45 pounds. Five, Kolleno, AI cash application for finance teams, per user.
Six, ezyCollect, Australian and New Zealand distributors on an ERP. Match the app to the situation you are in. Chapter four, under five overdue invoices a month, stay on Xero. 500,000 to 10 million turnover, lots of invoices, no credit controller.
The invoice priced add-on that does all four things. Past 4 million with a credit controller and a credit checking need, the suite. A finance team where cash application is the bottleneck, the AI platform.
Funding invoices as well as collecting them, the hybrid. Entry prices span about 10 times from under $100 a month to $650 per user. And two of the six price on turnover, not invoices.
Ask how the price moves before you ask what it is. That is credit control software for Xero. Send from your domain, write back to the ledger, schedule statements, and vary the rules by customer from an app that enforces what Xero only reports. The six-tool comparison is in the article at Paidnice.com.
Paidnice features in this article
About the editorial team
Denym started Paidnice in 2022 after customers paying late left his own business short on payroll. He has led it to $1 billion collected on time across more than 1 million invoices, and writes about credit control, late fees and getting paid on Xero and QuickBooks.
Ashley is a co-founder and lead developer of Paidnice and has built accounting software for more than 10 years. He builds the ledger connections that put reminders, late fees and payments into Xero, QuickBooks and ERPs such as NetSuite and Business Central. Before Paidnice he co-founded A2X, ecommerce accounting software for Xero and QuickBooks.
 App of the Year
