
Summary
Credit control software vs a debt collection agency comes down to timing: software chases every open invoice from the due date for a fixed monthly fee, in your name, and an agency takes over once an invoice is 60 to 90 days overdue, for a share of what it recovers.
- The trigger: Software fits the whole ledger from the due date; an agency fits the accounts that stop responding after your own reminders, statement, fee and escalation have run.
- What it costs: UK agency commission runs 5% to 25% of what is recovered; software is a flat fee whatever happens, Paidnice from £49 a month, priced by invoice volume, not revenue.
- Never pay commission on: Statutory interest at 8% over base rate and the £40, £70 or £100 fixed sum a UK supplier can add before any agency is involved.
Credit control software vs debt collection agency: what sets them apart?
Credit control software chases every invoice from your own address for a fixed fee; a debt collection agency recovers the invoices that have gone bad, in its own name, for a share of what comes back. Paidnice runs the software side, with reminders, statements, late fees and posted letters before any agency hand-over.
- Who sends. Credit control software sends reminders, statements, late fees and escalations in the supplier's name from the ledger in Xero or QuickBooks Online; a debt collection agency writes to the debtor under its own letterhead.
- When. Software starts at the due date on every open invoice; an agency takes over once an invoice is 60 to 90 days overdue and the debtor has stopped replying.
- Price model. Software is a fixed monthly subscription, Paidnice from £49 a month, priced by invoice volume, not revenue; an agency charges a contingency fee, a cut of the sum it brings in, so no win, no fee, and can escalate to legal action.
- Success measure. Software is judged on days sales outstanding (DSO) across the whole ledger; an agency is judged on the recovery rate of the accounts placed.
Most businesses need both, in that order: software on every invoice, then an agency for the few accounts that survive it, placed with the handover file attached.
This page covers business-to-business debt, where the collections process guide describes the in-house stage; consumer collections run under different rules and prices. The table sets the two options side by side on eight rows, and the sharpest line is cost: being wrong costs a month's fee with software and up to a quarter of the invoice with an agency.
| Credit control software | A debt collection agency | |
|---|---|---|
| The stage it covers | Due date onward, every invoice | 60 to 90 days overdue, the accounts you place |
| The sender on the message | Your name and your email domain | A third party, under its own letterhead |
| What you pay | A fixed fee, whatever happens | A share of what comes back |
| What it costs to be wrong | A month's fee | Up to a quarter of the invoice |
| Court route | None of its own: it posts the letter before action, the claim is yours or a solicitor's | Yes, via its solicitors, billed on top |
| Success measure | DSO falls across the ledger | Recovery rate on the accounts placed |
| What it leaves behind | A dated trail on the ledger | The file you sent, plus its notes |
| What happens to the account | Still trading | Often on stop, at your call |
To run the software side of that table on your own ledger, start a free Paidnice account: the first 20 actions are free, with no time limit and no card.
When should you hand an invoice to a debt collection agency?
Hand an invoice to a debt collection agency once it is 60 to 90 days overdue and the customer has not paid, replied or disputed after reminders, a statement, a late fee and a call from a named person.
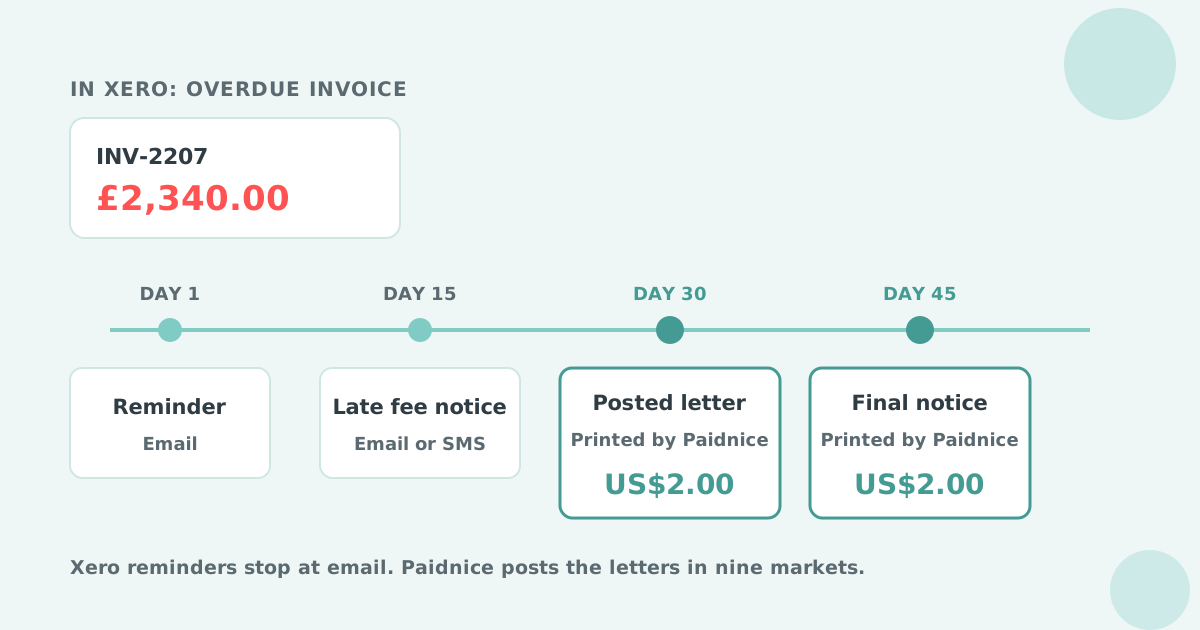
- Days 1 to 45: software, in your name. Reminders ahead of the due date and past it, a monthly statement, and the late fee and statutory interest posted to the ledger, all from your own address. In Paidnice the escalation trigger is days overdue, with a minimum due amount so small balances never escalate.
- Days 45 to 60: a person and a letter. An escalation to a named credit controller or director, a phone call logged against the invoice, and a posted final notice. Paidnice prints and posts letters at US$2.00 a letter, £1.50 in the UK, on the Pro plan and enabled on request. A solicitor-signed letter before action is priced case by case.
- Day 60 onward: the agency, with the reminder history. Stop your own reminders, export the dated trail and place the account, at the day count set out in when to send an overdue invoice to a collection agency. The agency starts from your evidence instead of rebuilding it at a percentage.

The video covers the same six points in three and a half minutes.
How much does credit control software cost compared with a debt collection agency?
Software costs a fixed fee whatever happens. An agency takes a share of what comes back. On the same £48,000 of overdue invoices, that is £674 against £12,000.
Take £48,000 of overdue invoices, which at an average invoice of £2,400 is 20 invoices. Place all of it with an agency at 25% and the fee is £12,000, so you keep £36,000.
Run credit control software first and assume reminders, statements and late fees resolve 95% of them, so 19 of the 20. One is placed at 25% for £600, plus £74 a month of software (Paidnice Pro 300, the tier that covers 300 invoices a month; the example assumes a volume that needs it), £674 in total, and you keep £47,326.
Paidnice starts at £49 a month for 150 invoices, no per-seat fee, no contract. The diagram below shows what a UK agency, a US agency and the software blend each leave you from one £2,400 invoice.

On the default ledger of 100 overdue invoices a month at £2,400, with software resolving 95% and the rest placed at 25%, the calculator shows £60,000 in agency fees as first resort against £3,074 for software plus the placed tail, £600 against £30.74 per overdue invoice. Change the 95% to test your own ledger.
Blended cost calculator
An agency as first resort against software plus the placed tail.
Agency as first resort
Software plus the placed tail (assumed)
The blend costs £56,926.00 a month less than an agency as first resort.
The share resolved by software is an assumption you set, not a measured rate. Fee is charged on the full invoice value, so every placed invoice is assumed recovered in full. Placed invoices are rounded to the nearest whole invoice. Interest and fixed sums recovered under the Late Payment Act are excluded from both columns. General information, not legal advice.
Does the age of a debt change what a collection agency costs you?
The agency's percentage stays flat while the collectable share of the debt falls: an undated member survey by Commercial Collection Agencies of America puts collectability at 95.1% on the due date and 8.9% at two years.
The survey is published by Commercial Collection Agencies of America.
Most UK invoices never get near three months. Xero Small Business Insights reports UK small businesses waited 29.1 days on average to be paid in the June 2026 quarter, with invoices 8.3 days late. Chase from the due date and the account never reaches that part of the curve.
What do UK and US debt collection agencies charge?
The typical UK agency commission range is 5% to 25% for commercial debts, per Northern Ireland's government business support service. The Kaplan Group, a US agency with a published range, quotes 10% to 50%. The US range is double the UK one at both ends.
The published UK headline rates from named firms: Safe Collections from 5% of the recovered amount, Federal Management from 6%, and Redwood Collections at a typical 15%. Budget on 25% as the UK ceiling, not any one agency's typical 15%.
Which statutory sums can you add before an agency is involved?
A UK business-to-business supplier can add a fixed sum of £40, £70 or £100 per invoice, statutory interest at 8% over the Bank of England base rate, and reasonable recovery costs above the fixed sum, before any agency or solicitor is involved.
The Late Payment of Commercial Debts (Interest) Act 1998 gives those rights to any UK supplier whose commercial customer pays late. The fixed sum is £40 on a debt under £1,000, £70 from £1,000 to £9,999.99 and £100 at £10,000 or more.
If the fixed sum and the interest do not move the customer, the next paid step is a letter before action and then a court claim, where the court fee is set by the size of the claim: £35 on a debt up to £300, rising to £455 between £5,000.01 and £10,000.
The point of claiming these first is leverage. A posted fixed sum and accruing interest on the ledger is a receivable the customer's accounts payable team can see.
If the account is placed anyway, the agency recovers the statutory sums with the rest and takes its commission on them too, so the only way to keep them whole is to have them paid before placement. Apply the sums automatically and waive them only on purpose.
A law firm chasing its own fee invoices can use accounts receivable software for law firms.
What do you give the agency at the handover?
The handover file an agency needs holds the debtor's legal name, every invoice, the signed terms, proof of delivery and a dated trail of every reminder, call, promise to pay or dispute. A thin file means the agency starts from your day-30 work, at a percentage.
Before you place, confirm on Companies House that the debtor is still trading, and check what your terms and privacy notice say about passing a customer's details to a collection agent. The dated collection history is the item most businesses cannot produce on demand, because it lives across an inbox, a phone log and someone's memory.
The tool you chase with decides whether the handover file already exists or has to be rebuilt from an inbox. When the pre-agency stage runs in credit control software, the trail exists because the chasing happened. In Paidnice:
- Escalations fire on documented triggers: days overdue, minimum and maximum due amount, total balance, credit-limit breach.
- Every reminder and statement is logged with delivery status.
- Notes and call outcomes sync to the invoice in Xero.
- Webhooks on the Pro plan fire on every completed or cancelled escalation.
That is the evidence package, produced as a by-product of chasing properly, and the handover becomes an export. The rungs are set out in the invoice escalation ladder.
Paidnice insight: the stage before an agency
Paidnice is the stage before an agency, never the agency itself. Customers running that stage cut their average wait for payment in half, within 30 days, and the accounts that still reach an agency arrive with the full trail attached.
What is the difference between credit management, credit control and debt collection?
Credit management is the whole process of deciding who gets credit and on what terms; credit control is the chasing of invoices once they are issued; debt collection is the recovery of the ones that go bad.
The three layers run in order:
- Credit management covers the credit check before the first order, the credit limit, the payment terms on the contract and the monitoring of the account afterward.
- Credit control sits inside it: the reminders, statements, fees and escalations that keep an issued invoice moving, run in-house, by software or as outsourced credit control.
- Debt collection starts where credit control stops, usually with an agency or a solicitor, and is measured by what is recovered.
In software the layers meet on one trigger: a Paidnice escalation can fire on a credit-limit breach or a customer's total balance as well as on a single invoice, so the credit limit drives the chasing.
Frequently asked questions
The questions below cover what a debt collector is, what a UK agency charges and whether credit control software replaces one. The short answers: credit control is the supplier's own chasing, a UK agency takes roughly 5% to 25% of what it recovers, and software runs the stage before any agency.
Is credit control a real debt collector?
No, credit control is not a debt collector: it is the supplier's own chasing of its invoices, run in-house or through software, in the supplier's name.
Credit control is not a licensed collector and recovers debt for nobody else. One naming collision: at least one US collection agency trades as Credit Control, so a US letter headed that way can come from an agency.
Is a debt collector the same as a collection agency?
A debt collector and a collection agency are nearly the same thing: a debt collector is any person or firm chasing a debt on a creditor's behalf, and a collection agency is a firm of them working on commission, never owning the debt. A debt buyer is different: it purchases the debt outright and collects for itself.
Does credit control software replace a debt collection agency?
No, credit control software does not replace a debt collection agency: software runs the stage before an agency, with reminders, statements, fees and escalations on every open invoice, in your name.
An agency takes the accounts that stop responding after that stage. Most businesses still place a small tail, and the blended cost of software plus that tail is a fraction of placing everything.
What does a UK debt collection agency charge on a commercial debt?
A UK debt collection agency takes roughly 5% to 25% of the sum it recovers on a commercial debt, per Northern Ireland's government-backed business support service. Named UK firms publish floors of 5% and 6% and a typical rate of 15%, with no ceiling stated.
A fixed-fee route also exists: Lovetts Solicitors prices a letter before action at £1.50 plus VAT by email, and a court claim on a £501 to £1,000 debt at £244: the £70 court fee plus £145 solicitor fee, with VAT on the £145.
Is it worth using a debt collection agency?
A debt collection agency is worth using for the accounts worth placing: it pursues the debts that reminders and calls did not recover, for roughly 5% to 25% of the sum recovered in the UK (per Northern Ireland's business support service) and 10% to 50% on The Kaplan Group's published US range.
On the example figures, placing 5 invoices in 100 at 25% costs £3,000 in fees, against £36,000 for placing all 100 at a negotiated 15%. Run the stage before the agency from the ledger, claim what the Late Payment Act gives you, and place the tail with the file complete.
Start a free Paidnice account: the first 20 actions are free, with no time limit and no card.
Stop chasing invoices.
Start getting paid.
Paidnice is accounts receivable automation that enforces your payment terms, trusted by thousands of businesses on Xero and QuickBooks. Credit control and debtor management, run for you.
Try it Now - It's FreeNo card required.