Summary
Outsourced credit control means hiring an external specialist firm to run part or all of your credit control on your behalf: credit checks, ledger monitoring, reminders, chasing calls, disputes and escalation, usually in your company's name. Paidnice is software that runs the routine chasing from your ledger; it is not an outsourced team.
- What it covers: Pre-due reminders, chasing by phone, email and letter, dispute logging, aged debt reports and escalation, often white-label so your customer only sees your name.
- How it is priced: Three common models: a fixed monthly retainer, a fee per invoice or account, or a percentage of the amounts collected.
- When software is enough: Paidnice runs reminders, statements, late fees and escalation from Xero or QuickBooks Online, from £49 a month for 150 invoices, priced by invoice volume, not revenue.
What is outsourced credit control?
Outsourced credit control is the practice of handing part or all of your accounts receivable follow-up to an external firm that manages it on your behalf, from credit checks and sales ledger monitoring through to reminders, chasing and escalation.
- Who does the work. The provider's credit controllers work inside your accounting system (Xero, QuickBooks or Sage) and usually write and call as your company, which is called white-label chasing.
- What it costs. Providers charge a monthly retainer, a fee per invoice or account, or a percentage of what is collected.
- What it is not. Outsourced credit control is not a debt collection agency, which takes over in its own name after the relationship has broken down, or invoice finance, which advances cash against unpaid invoices.
- Where software fits. Paidnice runs the routine layer from Xero or QuickBooks Online: reminders, statements, late fees and escalation. A person handles only the exceptions.
What does an outsourced credit control service include?
An outsourced credit control service in the UK typically runs eight tasks on your sales ledger, from confirming that an invoice arrived to handing an unpaid account to collection.
- Credit controllers call or email before the due date to confirm the customer received the invoice and to catch disputes early.
- The provider sends payment reminders and customer statements in your company's name.
- Credit controllers phone customers with overdue invoices and ask for a firm payment date.
- The provider records each promised payment date and calls again when the money does not arrive.
- Each dispute or query is logged and passed to a named contact to resolve.
- The provider runs credit checks on new customers and reviews their credit limits.
- You receive a monthly aged debt report with debtor days (DSO) and cash collected.
- Accounts that stay unpaid go to a debt collection agency or a solicitor, with your approval.
Paidnice runs the reminders, statements, promised-date pauses and escalations from Xero or QuickBooks Online. The calls, disputes and credit decisions on large accounts still need a person.
What are the benefits of outsourcing credit control?
The benefits of outsourcing credit control are specialist chasing skills, a cost that moves with your invoice volume, cover through holidays and sickness, and a neutral third party on difficult calls.
- Expertise. Provider staff chase daily and know when a call beats another email.
- Variable cost. A retainer or per-invoice fee replaces a fixed salary and recruitment.
- Continuity. Chasing continues when a member of staff leaves, is ill or is on holiday.
- Consistency. Reminders go out on a set timetable instead of in bursts around month-end.
How much does outsourced credit control cost?
Outsourced credit control cost depends on the pricing model: a fixed monthly retainer, a fee per invoice or account, or a percentage of the amounts collected.
| Pricing model | How it is charged | Suits |
|---|---|---|
| Monthly retainer | A fixed fee for a set number of invoices or hours | Steady invoice volume |
| Per invoice or account | A fee for each invoice or customer chased | Low or uneven volume |
| Percentage of collected | A share of the sum recovered | Older, harder debt |
A percentage of what is collected is how debt collection agencies charge. The commission ranges for UK and US agencies are set out in credit control software vs a debt collection agency.
Compare every option on cost per invoice covered: the monthly fee divided by the invoices it covers. Paidnice Essentials is £49 for 150 invoices a month, about 33p an invoice or £588 a year. Paidnice Pro 600 is £129 for 600 invoices, about 22p an invoice. Paidnice plans are priced by invoice volume, not revenue, with no contract.
Run the same sum on an outsourced quote: the retainer divided by the invoices covered, plus any call-hour or letter charges. For an in-house hire, divide the full salary cost by the invoices that person chases in a year.
What are the downsides of outsourcing credit control?
The downsides of outsourcing credit control are less control over tone and timing, a third party inside your accounting data, and fees that keep running whether or not the ledger is clean.
- Control and tone. Someone outside the business decides how firm to be with a customer you may want to keep.
- Data access. The provider needs logins to Xero, QuickBooks or Sage and your customer contacts, so you need a data processing agreement with them.
- Disputes. Chasing does not fix a wrong invoice or a missing purchase order; those go back to your team.
- Exit. The minimum term and notice period decide how fast you can bring chasing back in house.
Is outsourced credit control the same as debt collection?
Outsourced credit control is not the same as debt collection: credit control keeps a trading customer paying on time in your name, while a debt collection agency recovers debt in its own name after the relationship has failed.
Credit control starts before the due date and covers every invoice. Debt collection starts after your reminders, statements and calls have failed, and covers only the accounts you place, usually for a share of what is recovered.
When should you outsource credit control?
Consider outsourcing credit control when aged debt keeps growing, chasing happens only when someone has a spare hour, or a director is the person phoning customers.
- Outsource when aged debt over 60 days grows each month.
- Outsource when the owner does the chasing.
- Outsource when nobody chases during holidays.
Before you ask for quotes, count three things: the hours a week spent chasing, who covers chasing during holidays, and how many accounts sit over 60 days. If the gap is reminders that do not go out on time, software closes it. If the gap is calls and disputes on large accounts, people are the fix.
When is credit control software enough?
Credit control software is enough when most overdue invoices pay after a clear, timely reminder, and the work left over is a handful of disputes and calls a week.
In-house, outsourced and software credit control differ most on cost model, control over tone, cover during absence and what you still own.
| Credit control option | In-house | Outsourced | Software |
|---|---|---|---|
| Cost model | A salary | Retainer, per invoice or % | Monthly subscription |
| Control and tone | Full | Shared with the provider | Your rules and templates |
| Cover when staff are away | Gaps | Provider covers | Runs on schedule |
| What you still own | Everything | Terms, disputes, data | Terms, disputes, calls |
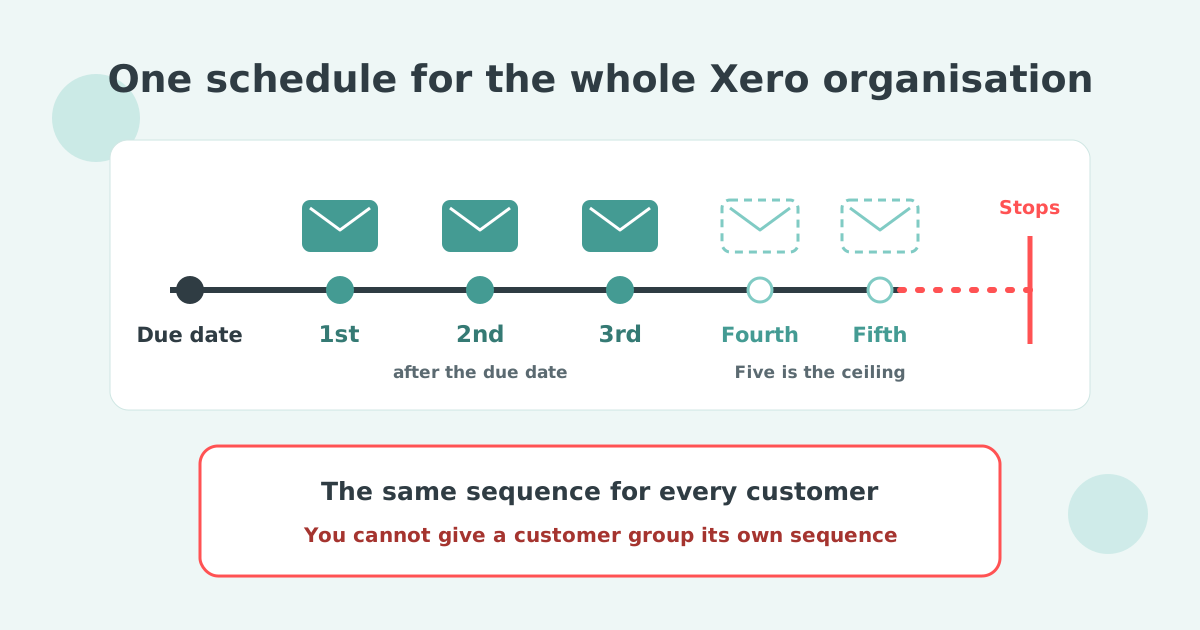
- Paidnice sends email and SMS reminders before, on and after the due date.
- Paidnice sends customer statements on a weekly or monthly schedule.
- Paidnice adds late fees and statutory interest, with the Bank of England base rate indexed automatically.
- Paidnice raises an escalation at a set number of days overdue: a phone call task, stop credit or a template legal letter.
Reminders and statements on their own are a complete setup; late fees are optional. Paidnice keeps a person on the exceptions with four settings:
- Manual run mode. A policy set to Manual holds each action as Pending until someone approves it.
- Expected payment date. When a customer promises a date, chasing pauses on that invoice and resumes if it is still unpaid.
- Minimum due amount. An escalation fires only above the amount you set, so small balances never reach a person.
- Owner assignment. Each customer or escalation can have a named owner, and customer replies land inside Paidnice.
Your team keeps the exceptions: disputes, key accounts and hardship. See credit control without a credit controller for the split and credit control software for the product. To try Paidnice on your own ledger, start a free account: the first 20 actions are free, with no time limit and no card.
How do you choose an outsourced credit control provider?
Choose an outsourced credit control provider by checking how it chases in your name, which accounting systems it works in, what it reports, and how easily you can leave.
- White-label. Does the provider write and call as your company, from your domain?
- Integration. Does the provider work inside Xero, QuickBooks or Sage, or ask for exports?
- Contract and exit. What are the minimum term and notice period, and how do your data and notes come back?
Common questions about outsourced credit control
Outsourced credit control sits between in-house chasing and debt collection, so most related questions ask where one ends and the next begins.
What are the two main types of credit control methods?
The two main credit control methods are proactive and reactive. Proactive work comes before the due date: credit checks, clear terms and pre-due reminders. Reactive work comes after it: chasing, late fees and escalation.
What is outsourced debt collection?
Outsourced debt collection hands overdue accounts to an agency that recovers them in its own name for a percentage of what it collects. Before that step, a UK supplier can add statutory interest at base rate plus 8%, 11.75% a year for the half-year from 1 July 2026, and a fixed sum of £40, £70 or £100.
What does it mean to outsource delinquent accounts?
To outsource delinquent accounts is to pass seriously overdue accounts, the ones that have ignored reminders and calls, to an external collector. Paidnice can raise a template legal letter as an escalation first, at a set number of days overdue.
Stop chasing invoices.
Start getting paid.
Paidnice is accounts receivable automation that enforces your payment terms, trusted by thousands of businesses on Xero and QuickBooks. Credit control and debtor management, run for you.
Try it Now - It's FreeNo card required.